Creating a Church Budget That Honors God and Serves Your Community

A well-crafted church budget is more than a financial document, it’s a reflection of your congregation’s values, priorities, and commitment to faithful stewardship. Creating a budget that honors God while effectively serving your community requires careful planning, transparent communication, and a clear understanding of your ministry’s mission and goals.

Understanding Biblical Stewardship in Church Budgeting

Biblical stewardship forms the foundation of responsible church financial management. This principle recognizes that all resources belong to God, and churches serve as stewards entrusted with managing these gifts wisely. Your budget should reflect this understanding by:

  • Prioritizing ministries that align with your church’s biblical calling and mission
  • Ensuring transparency in all financial decisions and allocations
  • Planning for generosity through missions and community outreach funding
  • Maintaining fiscal responsibility to preserve resources for future ministry


When your budget reflects biblical principles, it becomes a tool for spiritual growth and community impact rather than just financial management.

Stewardship extends beyond managing money to encompass time, talents, and opportunities. Your budget should consider how financial decisions affect volunteer engagement, staff development, and community relationships. This holistic approach ensures that budgeting decisions support your church’s overall ministry effectiveness.

Essential Components of a Church Budget

Every effective church budget consists of four main categories that work together to support ministry operations and growth. Understanding these components helps ensure comprehensive planning that covers all aspects of church life.

1. Personnel 

Personnel expenses typically represent 45-65% of most church budgets and include:

  • Pastoral and staff salaries with appropriate benefits and professional development opportunities
  • Support staff compensation for administrative, maintenance, and childcare roles
  • Contract services for specialized needs like music direction or technical support
  • Benefits packages covering health insurance, retirement contributions, and continuing education


2. Facility and Operations 

Facility and operations costs maintain the physical foundation for ministry activities:

  • Building maintenance including repairs, cleaning, and safety inspections
  • Utilities such as electricity, heating, cooling, water, and internet services
  • Insurance coverage for property, liability, and worker protection
  • Capital improvements that enhance ministry effectiveness and community welcome


3. Ministry and Outreach Programs

Ministry and outreach programs fund the heart of your church’s mission:

  • Worship and music ministries with instruments, sound equipment, and special events
  • Educational programs covering children’s ministry, youth activities, and adult discipleship
  • Community outreach including service projects, food pantries, and relationship building
  • Missions support for both local partnerships and international ministry work


4. Administrative Operations

Administrative operations provide the organizational backbone that keeps everything running smoothly. These expenses cover office supplies, communication systems, financial management tools, and legal compliance requirements. AGCU’s ministry banking services can help streamline these administrative costs while providing specialized financial tools designed specifically for church operations.


The Budget Planning Process

Effective budget planning begins months before the fiscal year starts, typically involving multiple stakeholders and careful consideration of ministry priorities. Start by reviewing the previous year’s financial performance to identify trends, successful programs, and areas needing adjustment.

Engage ministry leaders in the planning process by asking each department to submit budget requests with detailed justifications. This collaborative approach ensures that:

  • Ministry needs are accurately represented in budget allocations
  • Department leaders feel ownership in the budgeting process
  • Resource allocation reflects actual ministry priorities and goals
  • Communication improves between leadership and ministry teams


Conduct a thorough assessment of your church’s financial capacity by analyzing giving patterns, membership trends, and economic factors affecting your congregation. Consider both optimistic and conservative scenarios to prepare for various financial outcomes.

Set realistic goals that balance ministry expansion with financial sustainability. While faith requires stepping out in trust, wisdom demands careful planning that doesn’t jeopardize the church’s long-term stability or ability to meet existing commitments.

Balancing Ministry Priorities with Financial Reality

One of the greatest challenges in church budgeting involves aligning ministry aspirations with available resources. This balance requires honest assessment of priorities and creative problem-solving to maximize ministry impact within financial constraints.

Create a tiered approach to budget planning with essential, important, and aspirational categories. Essential items include:

  • Core operational expenses like utilities, insurance, and basic staffing
  • Fundamental ministry programs that directly support your church’s primary mission
  • Legal and compliance requirements including payroll taxes and facility safety
  • Emergency reserves for unexpected expenses or income shortfalls


Essential items support ministry growth and community engagement but can be adjusted if necessary. Aspirational items represent opportunities for ministry expansion when additional resources become available.

Consider alternative funding strategies for ministry initiatives beyond the general budget. Special offerings, fundraising events, designated giving campaigns, and partnership opportunities can support specific projects without straining regular operations.

Regularly evaluate program effectiveness to ensure budget allocations produce meaningful ministry outcomes. Programs that consistently underperform or fail to align with your church’s mission may need modification or elimination to free resources for more effective initiatives.

Building Transparency and Accountability

Financial transparency builds trust and encourages greater congregational engagement in stewardship. Share budget information openly while maintaining appropriate confidentiality around personnel details. Effective transparency includes:

  • Annual budget presentations explaining major allocations and ministry priorities
  • Quarterly financial updates showing income, expenses, and budget variance
  • Ministry impact reports demonstrating how financial investments support church mission
  • Clear communication about special needs, challenges, and opportunities


Establish strong internal controls to protect church resources and maintain financial integrity. These controls should include multiple signature requirements for significant expenses, regular financial reviews by board members, and clear policies for expense authorization and reimbursement.

Consider having an annual independent financial review or audit, especially for larger churches or those receiving significant donations. This external validation provides additional accountability and can identify opportunities for improved financial management.

Create systems for regular budget monitoring and adjustment throughout the year. Monthly reviews allow for course corrections when income or expenses vary significantly from projections, preventing small issues from becoming major problems.

Technology and Tools for Budget Management

Modern church budget management benefits significantly from appropriate technology solutions. Church management software can integrate giving records, membership data, and financial tracking to provide comprehensive financial oversight.

Key technological features to consider include:

  • Automated giving tracking that categorizes donations and generates tax statements
  • Expense management tools for tracking purchases against budget categories
  • Financial reporting capabilities that produce clear statements for leadership review
  • Integration with banking services for streamlined account management and reconciliation


Online giving platforms expand donation opportunities while reducing administrative burden. These systems allow congregation members to give consistently through automatic transfers while providing churches with more predictable income streams.

Cloud-based solutions offer security, accessibility, and backup protection for financial data while enabling remote access for authorized personnel. This flexibility becomes especially valuable during times when traditional office access may be limited.

Planning for Unexpected Challenges

Every church budget should include contingency planning for unexpected situations that could significantly impact finances. Recent years have demonstrated the importance of financial flexibility in maintaining ministry operations during challenging circumstances.

Build emergency reserves equivalent to three to six months of operating expenses. This financial cushion provides stability during:

  • Economic downturns that may reduce congregational giving
  • Facility emergencies requiring immediate repair or replacement
  • Health crises that interrupt normal church operations and income
  • Leadership transitions that may temporarily affect giving patterns


Develop multiple scenarios for budget implementation based on different income levels. Having pre-planned adjustments helps leadership respond quickly to changing circumstances without compromising essential ministries.

Consider insurance coverage that protects against various risks including property damage, liability claims, and business interruption. While insurance represents an expense, it provides crucial protection for your church’s financial stability.

Frequently Asked Questions

Q: What percentage of the budget should go to staff salaries? 

A: Personnel costs typically range from 45-65% of church budgets, depending on church size and ministry model. Larger churches may have lower percentages due to economies of scale, while smaller churches often allocate higher percentages to essential staffing.

Q: How much should churches allocate for missions and outreach? 

A: Many churches aim for 10-20% of their budget for missions and outreach, though this varies based on church priorities and community needs. Some churches designate specific offerings for missions beyond the general budget.

Q: Should churches borrow money for facility improvements? 

A: Church borrowing can be appropriate for necessary facility improvements or expansion that supports ministry growth, but it should be carefully planned with realistic repayment schedules that don’t compromise other ministry areas.

Q: How often should church budgets be reviewed and updated?

 A: Churches should review budgets monthly and make adjustments quarterly as needed. Annual budget planning should begin 3-4 months before the fiscal year starts to allow adequate preparation time.

Q: What’s the best way to handle budget shortfalls? 

A: Address shortfalls through a combination of expense reduction, increased communication about giving, and possible use of reserves. Avoid borrowing for operational expenses when possible.

Q: How can small churches create effective budgets with limited resources? 

A: Small churches should focus on essential functions, consider shared resources with other churches, utilize volunteers effectively, and explore partnership opportunities to maximize ministry impact within budget constraints.

Partner with AGCU for Faithful Financial Stewardship

Creating and managing a church budget that honors God requires the right financial partnership to support your stewardship goals. AGCU understands the unique challenges churches face in balancing ministry priorities with fiscal responsibility.

Our ministry banking solutions provide the tools and support your church needs for effective budget management. From specialized checking accounts designed for ministry operations to online banking features that streamline financial oversight, AGCU helps churches focus on ministry while maintaining excellent financial stewardship.

Ready to enhance your church’s financial management? Contact AGCU at 866-508-2428 or explore our ministry services at agcu.org/ministry to discover how faith-based banking can support your church’s budgeting goals. Let us help you manage your resources faithfully so you can concentrate on the ministry work God has called you to do.
 

12 Steps to Financial Wellness-Step 3: Pay Down Debt

12 Steps to Financial Wellness

Step 3: Pay Down Debt

Create a practical payoff plan, reduce the cost of borrowing and take another important step toward greater financial freedom.

Your Financial Wellness Journey Step 3 of 12

You have tracked your spending and created a budget for your monthly expenses. Now it is time to use what you have learned to address one of the biggest obstacles to financial wellness: debt.

Paying down debt may take time, but you do not have to tackle everything at once. A clear plan, consistent payments and steady progress can help you regain control of your finances.

1

Organize Your Debt

Start by creating a complete list of the money you owe. Include credit cards, personal loans, vehicle loans, medical debt, student loans and any other outstanding balances.

For each debt, record:

  • The name of the lender or creditor
  • Your current balance
  • The interest rate
  • Your required minimum payment
  • The monthly due date

Seeing all your debts in one place can feel intimidating, but it gives you the information you need to create an effective payoff strategy.

Creditor Balance Interest Rate Minimum Payment Due Date


2

Choose Your Payoff Strategy

Two common debt-payoff strategies are the debt snowball and the debt avalanche. Both can work. The best choice is the one that keeps you motivated and fits your financial circumstances.

Motivation Focused

Debt Snowball

Make the minimum payment on every debt, then direct all available extra money toward your smallest balance.

When that debt is paid off, apply its former payment to the next-smallest balance.

Potential advantage: Paying off smaller debts quickly can provide encouragement and build momentum.

Interest Focused

Debt Avalanche

Make the minimum payment on every debt, then direct all available extra money toward the balance with the highest interest rate.

After that debt is paid, move to the debt with the next-highest rate.

Potential advantage: This approach may reduce the total amount of interest you pay.

3

Increase Your Payments

Minimum payments can keep an account current, but they may not reduce the balance very quickly—especially when the interest rate is high. Look for realistic ways to add more to your targeted debt each month.

  • Reduce spending in one or two flexible budget categories.
  • Cancel subscriptions or services you no longer use.
  • Apply bonuses, gifts or other unexpected income to your debt.
  • Use part of a tax refund for an additional principal payment.
  • Sell unused belongings and apply the proceeds to your balance.
  • Consider temporary freelance, overtime or part-time work.

You do not need a large amount of extra money to make progress. Consistently adding even a modest amount to your payment can reduce your balance and shorten your payoff timeline.

4

Consider Debt Consolidation

Debt consolidation combines multiple balances into a single loan. If the new loan has a lower interest rate and affordable payment, consolidation may make your debt easier to manage and reduce the amount of interest you pay.

Before consolidating, compare:

  • The new interest rate and annual percentage rate
  • Any origination fees or other loan costs
  • The length of the repayment term
  • The total amount you will repay over the life of the loan
  • Whether the monthly payment fits comfortably within your budget

A lower monthly payment is not always a better deal if it extends the debt for several additional years. Review the full cost—not only the payment amount.

5

Talk With Your Creditors

Contacting a creditor may feel uncomfortable, but asking about your options can be worthwhile—especially before you miss a payment.

Depending on the lender and your circumstances, options may include:

  • A lower interest rate
  • A temporary hardship plan
  • A modified payment schedule
  • A changed payment due date
  • Waived or reduced fees

Explain your situation honestly, ask what assistance may be available and make sure you understand the terms before agreeing to a new payment arrangement.

Your Debt-Payoff Action Plan

  • List every outstanding debt and its details.
  • Select the snowball or avalanche method.
  • Decide how much extra you can pay each month.
  • Set up automatic minimum payments when appropriate.
  • Track your declining balances and celebrate milestones.
  • Review your plan whenever your income or expenses change.

Could Consolidating Your Debt Help?

An AGCU personal loan may help you combine eligible balances into one predictable monthly payment. Compare the rate, term and total cost carefully to determine whether consolidation is appropriate for your financial situation.

Explore Personal Loans Contact AGCU
Important: This article is provided for general educational purposes and is not financial, legal, credit or tax advice. Loan approval, rates and terms are subject to creditworthiness, eligibility and AGCU underwriting requirements. Consolidating debt may not reduce your total repayment cost in every situation. Membership eligibility applies. Federally insured by NCUA.

12 Steps to Financial Wellness-Step 2: Creating a Budget

12 Steps to Financial Wellness

Step 2: Create a Budget

Turn what you learned by tracking your spending into a practical plan for paying expenses, reaching goals and using your money with purpose.

Your Financial Wellness Journey Step 2 of 12

A budget is not a punishment or a list of everything you are not allowed to buy. It is a plan for your money. A thoughtful budget helps you cover your responsibilities, prepare for future expenses and make room for the things that matter most to you.

If you completed Step 1 and tracked your spending, you already have much of the information you need. Now you can use those numbers to build a realistic monthly plan.

1

Calculate Your Monthly Income

Begin with the money you can reasonably expect to receive each month. Use your take-home pay—the amount available after taxes, insurance and other payroll deductions.

  • Paychecks from regular employment
  • Self-employment or freelance income
  • Social Security, pension or retirement income
  • Child support or other dependable payments
  • Any additional income you receive consistently

If your income changes from month to month, consider using a conservative average based on several months of earnings. Building your budget around a lower, dependable amount can help you avoid committing money that may not arrive.

2

List Your Monthly Expenses

Review your statements, bills and spending records. Include both fixed expenses that stay about the same and variable expenses that may change from month to month.

Expense Type Examples Budgeted Amount
Housing Mortgage or rent, utilities, insurance and maintenance $
Transportation Vehicle payment, fuel, insurance, repairs and transit $
Food Groceries, dining out, coffee and convenience purchases $
Debt Payments Credit cards, loans, medical debt and student loans $
Savings and Goals Emergency savings, retirement, vacations and major purchases $
Personal and Family Clothing, childcare, entertainment, hobbies and subscriptions $
Giving Tithes, charitable donations and community support $
3

Separate Needs From Wants

Needs are expenses required for basic living, health, safety and financial obligations. Wants are purchases that may improve your comfort or enjoyment but can usually be reduced, delayed or replaced when necessary.

The distinction is not always simple. Internet access may be a necessity for work or school, while a premium entertainment package is likely a want. Groceries are a need, while frequent restaurant meals are generally more flexible. The goal is not to criticize your choices—it is to understand where you have room to adjust.

  • Needs: Housing, basic utilities, food, medicine, transportation and required debt payments
  • Wants: Entertainment, optional subscriptions, upgrades, hobbies and convenience spending
  • Goals: Savings, investing, giving and planned future purchases
4

Assign Every Dollar a Purpose

Compare your expected income with your planned expenses. Your budget should account for the full amount of money available, including amounts designated for savings, giving and financial goals.

Monthly Income − Planned Expenses − Savings and Goals = $0 Unassigned

A zero-based plan does not mean spending every dollar. It means every dollar has a job. Money directed toward an emergency fund, retirement account or future expense is still part of the plan.

If your expenses exceed your income, begin by reviewing flexible categories. Look for changes that are realistic and sustainable rather than cutting every enjoyable expense at once.

5

Choose a Budgeting System

There is no single budgeting method that works for everyone. Consider your personality, financial responsibilities and preferred level of detail.

Traditional Category Budget

Set a monthly limit for each spending category, then review your transactions throughout the month. This method works well for people who prefer detailed planning and regular tracking.

Envelope System

Assign cash—or digital spending limits—to flexible categories such as dining, entertainment and personal spending. When the category is empty, spending stops until the next budget period.

50/30/20 Framework

As a general guideline, direct about 50% of take-home pay to needs, 30% to wants and 20% to savings and debt repayment. Your actual percentages may need to differ based on housing costs, income and family needs.

6

Review and Adjust Your Plan

Your first budget is a starting point, not a permanent contract. Review your spending during the month and compare it with your plan. Adjust categories when costs change or when your original estimate was unrealistic.

  • Review transactions at least once each week
  • Adjust for seasonal bills and annual expenses
  • Update your plan after changes in income or household needs
  • Include a small cushion for expenses that are difficult to predict
  • Revisit your goals and priorities regularly

A budget should become more accurate over time. Learning from each month is part of the process.

This Month’s Budget Challenge

Create a complete budget for the upcoming month before it begins. Schedule a short weekly check-in to compare your plan with your actual spending. At the end of the month, identify one category that worked well and one that needs adjustment.

Keep Your Budget Connected to Your Accounts

AGCU Online Banking can help you review transactions, monitor account activity and stay aware of your spending throughout the month. Regular check-ins make it easier to keep your budget current and make adjustments before small problems become larger ones.

Log In to Online Banking Explore Digital Banking
Important: This article is provided for general educational purposes and is not financial, legal, credit or tax advice. Digital Banking features and availability may change. Membership eligibility applies. Federally insured by NCUA.

Your Complete Year-End Financial Checklist

Is your monthly budget still working well for you? Are you stretching some spending categories or finishing each month in the red? Take some time to review your budget and make any necessary changes.

Insurance Check-up New Year Resolution

Start the new year with an insurance check-up

AGCU Insurance

Make an Insurance Check-Up Your New Year’s Resolution

Life changes. Your insurance needs can change with it. Start the new year by making sure your coverage still fits your life.

Insurance isn’t a “buy it and forget it” product. As your life changes, your insurance needs may change too.

An annual insurance check-up gives you a chance to review your current policies, make sure you have the coverage you need, look for gaps, and see whether there may be opportunities to save.

Make it an annual habit. Pick a time each year to review your insurance. The beginning of a new year is an easy reminder to check in and make sure your coverage still works for you.

Has Anything Changed This Year?

You don’t have to wait for your annual review if something important changes in your life. A major life event is a good reason to take another look at your coverage.

Marriage or Divorce
A New Child
A New Home
A New Vehicle
Job or Income Changes
Home Improvements
New Debt or Obligations
Lifestyle Changes

Review Your Home, Auto and Property Coverage

Your property and insurance needs can change from year to year. An annual review can help you make sure you’re not paying for coverage you no longer need — or missing protection you do need.

Take a few minutes to ask:

  • Have I bought or sold a vehicle?
  • Have I renovated, remodeled or added onto my home?
  • Have I purchased valuable items that may need additional coverage?
  • Have my driving habits changed?
  • Do my current deductibles still make sense for my budget?
  • Could I qualify for new discounts or save by combining policies?
It can pay to compare. Reviewing your coverage and rates can help you determine whether you’re still getting the protection and value you need.

Don’t Forget

Review Your Life Insurance, Too

When you first purchased life insurance, you probably considered your family’s needs, income, financial obligations and future goals. Those things can change over time.

During your annual review, consider:

  • Has your family grown or changed?
  • Does your current coverage amount still meet your family’s needs?
  • Have your income, debt or financial obligations changed?
  • Are your beneficiaries still correct?
  • Has your address or other important information changed?
  • Have you made significant health or lifestyle changes?
  • When does your term policy expire?

Your insurance professional can help you review your current policy and determine whether changes may be appropriate.

Four Questions to Ask During Your Insurance Check-Up

1. What coverage do I have?

Make sure you understand what each policy covers — and what it doesn’t.

2. How much coverage do I need?

Consider whether changes in your home, family, income or responsibilities have changed your needs.

3. Can I lower my premiums?

Ask whether different coverage options or available discounts could help lower your costs.

4. Are my deductibles and discounts still right?

Review your deductibles and make sure you’re receiving any discounts you may qualify for.

More Than Home and Auto

AGCU Insurance offers more than 20 types of insurance. Depending on what changed in your life this year, you may need coverage you didn’t need before.

  • Auto, Motorcycle and Scooter
  • Boat, ATV and Recreational Vehicle
  • Life Insurance
  • Home, Condo and Vacation Home
  • Wedding Insurance
  • Landlord Policies
  • Renters Insurance
  • Pet Insurance
  • Valuable Items Coverage
  • Flood, Sinkhole and Disaster-Related Coverage

Check for Ways to Save

An insurance review isn’t only about coverage. It’s also a chance to make sure you’re getting a competitive price.

Depending on the policy and carrier, discounts may be available for things like multiple vehicles, multiple drivers, newer vehicles, paperless billing, combining policies, good students and more.

AGCU Insurance offers free coverage check-ups, so you can review both your protection and your potential savings.

AGCU Insurance

Start 2027 With a Free Insurance Check-Up

Take a little time now to make sure your coverage still fits your life. An AGCU Insurance professional can help you review your policies, answer your questions and explore your options.

866-508-2428 or 417-447-9356
insurance@agcu.org

Visit AGCU Insurance

AGCU Insurance directly serves members in Arkansas, Kansas, Missouri, Oklahoma and Texas. If you live outside these states, contact AGCU Insurance for information about available options.

A Resolution Worth Keeping

Life rarely stays exactly the same from one year to the next. A quick insurance review can help make sure your protection keeps up.

Banking with a Purpose.

Holiday Skip-a-Pay

Holiday Skip-a-Pay

Need some extra cash this holiday season? You may be eligible to skip your consumer loan payment in November or December!*

Consumer Loans include:

  • Auto Loans
  • Boat Loans
  • Motorcycle Loans
  • RV Loans
  • Personal Lines of Credit
  • Signature Loans

Simply download and fill out the “Holiday Skip-a-Pay” form. Then send it to one of the following:

Email: skipapay@agcu.org

Fax: 417.831.4420

Mail: AGCU (Attn: Skip-a-Pay), PO Box 2328, Springfield, MO 65801

Click here to download the form.

Loans financed elsewhere? You may be able to lower your rate and payment by refinancing with us, and you can delay your first payment up to 30 days.

Banking With A Purpose

Much more than a catchphrase, our tagline is our passion, our reason why we do what we do. This is the impact of your membership with AGCU. Learn More About Banking with a Purpose

Like us on Facebook!

________________________________________________________________________

*CONSUMER CREDIT CARDS, REAL ESTATE LOANS, HELOC LOANS, BUSINESS LOANS, AND BUSINESS CREDIT CARDS ARE EXCLUDED FROM THIS OFFER. Skip-a-Pay Processing fee of $25.00 or 10% of the monthly payment – up to $50.00 (whichever is the greater amount). Maximum of two (2) payments may be skipped per loan, per calendar year. Maximum of four (4) payments may be skipped over the life of the loan. Interest will continue to accumulate on the loan during the month the payment is skipped. All loans must be current to qualify and must have been opened at least 60 days prior to the month of loan payment skipped. Only loans that have had the first monthly payment since origination are eligible for the Holiday Skip-A-Payment program.

If the processing fee is not paid, this offer is void. Offer expires 12/31/2025

5 Reasons To Open A Money Market Account

Five Reasons to Open a Premier Money Market Account

Save More. Keep Your Options Open.

Five Reasons to Open a Premier Money Market Account

When you’re trying to save and manage your money, choosing the right account isn’t always simple. A traditional savings account is a great place for money you’re setting aside, while checking is designed for everyday spending. But what if you want your savings to work harder while still keeping your money accessible?

That’s where a money market account can help. AGCU’s Premier Money Market Account combines competitive dividend rates with convenient access to your funds, making it an option worth considering for larger balances you want to keep available while they grow.

Reason 1: Accessibility of Funds

Reason #1

Your Money Stays Accessible

One of the biggest advantages of a money market account is liquidity. Unlike a certificate, your money isn’t committed to a specific maturity date or term.

That can make a Premier Money Market Account useful for funds you aren’t planning to spend today but may need in the future—for things like tuition, home repairs, a major purchase or an unexpected expense. Your money can continue earning dividends while it waits for its next purpose.

 
Reason 2: You Are in Control

Reason #2

You Stay in Control

Saving doesn’t have to mean putting your money somewhere that’s difficult to reach.

A Premier Money Market Account gives you flexibility in managing your funds. You can make deposits, write checks, make withdrawals and transfer money when you need it.

Premier Money Market Accounts allow up to six withdrawals or transfers per month. This makes it easier to access your savings when you need it while still encouraging you to keep those funds working toward your financial goals.

Whether you’re building savings for tomorrow or preparing for a large expense, you retain access to your money without committing it to a fixed certificate term.

Reason 3: Competitive Dividend Rates

Reason #3

Put a Larger Balance to Work

Money market accounts can offer stronger earning potential than a traditional savings account while allowing you to maintain access to your funds.

AGCU’s Premier Money Market Account uses a tiered rate structure: as your qualifying balance increases, so does the opportunity to earn a higher dividend rate.

Current Premier Money Market Rates

Premier Money Market Account

Minimum Balance APR APY
$50,000–$74,999 3.25% 3.29%
$75,000–$99,999 3.50% 3.55%
$100,000+ 3.75% 3.81%

Dividends compounded monthly. Rates accurate as of 03/02/2026.

APY = Annual Percentage Yield. APR = Annual Percentage Rate. Rates subject to change.

A minimum balance of $50,000 is required to earn dividends. There is a $10 monthly fee if your balance falls below $50,000.

 
Reason 4: Security

Reason #4

Save with Confidence

Growth matters—but so does knowing where your money is.

Funds held in qualifying accounts at AGCU are federally insured by the National Credit Union Administration, subject to applicable coverage limits and rules. That gives members an opportunity to build savings without exposing those deposited funds to the day-to-day fluctuations of the stock market.

Federally Insured Savings

Member deposits are federally insured by the NCUA in accordance with federal insurance rules and coverage limits.

Reason 5: Banking with a Purpose

Reason #5

Your Savings Can Do More

At AGCU, saving isn’t only about what your money can do for you. It’s also about what your financial partnership can help make possible for others.

AGCU serves individuals, families, churches, ministries and businesses with financial tools designed to help them grow and thrive. Deposits help provide the resources AGCU uses to make loans that support homes, businesses, churches and ministries throughout the Assemblies of God community.

That’s Banking with a Purpose.

Ready to Get Started?

Put Your Savings to Work

Open a Premier Money Market Account or talk with an AGCU representative about whether it’s the right option for your financial goals.

Have questions about membership or opening an account? Call AGCU at (417) 831-4398 or contact us online.

APY = Annual Percentage Yield. APR = Annual Percentage Rate. Dividends compounded monthly. Rates accurate as of 03/02/2026. Rates subject to change.

A minimum balance of $50,000 is required to earn dividends. There is a $10 monthly fee if your balance falls below $50,000.

AGCU — Banking with a Purpose.

Your Membership Matters

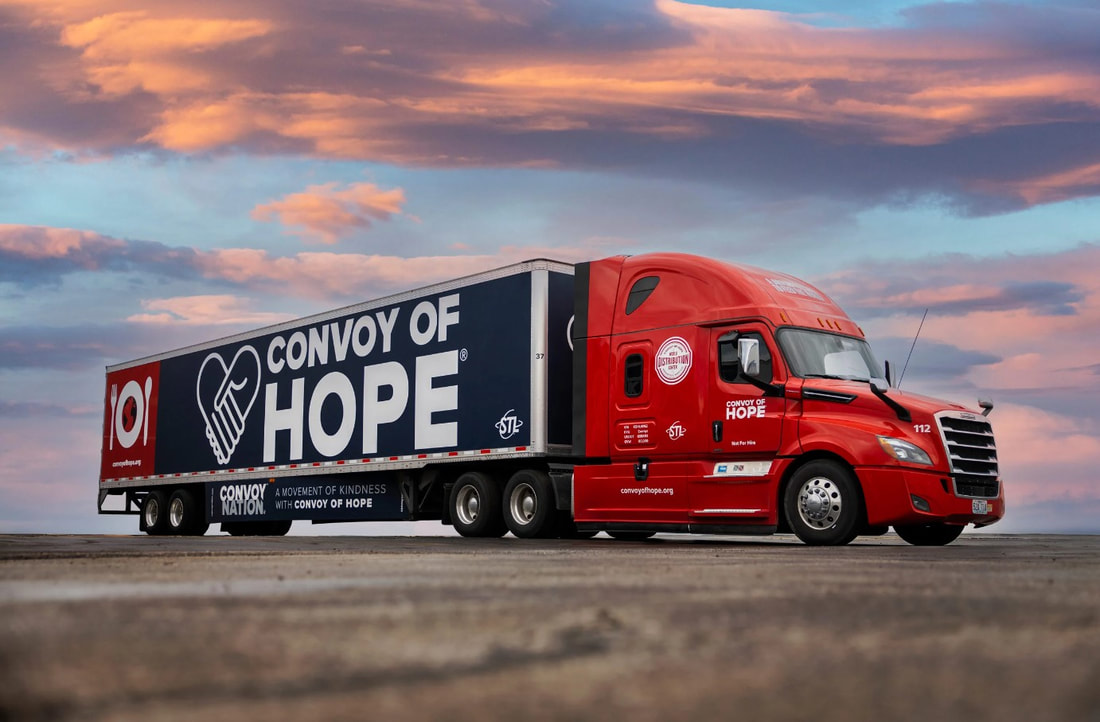
Convoy Of Hope Tractor-trailer

12 Days of Impact

At the Assemblies of God Credit Union, your membership actively supports ministry, education, and humanitarian causes. It’s more than just banking; it’s a faith-driven financial partnership we call Banking With A Purpose.

In the spirit of the holidays, let’s celebrate “12 Days of Impact” as we reflect on the incredible contributions your membership at AGCU makes to these and many more initiatives. Your membership truly matters, creating ripples of positive change that resonate far beyond the realms of traditional banking. As we step into the new year, let’s continue to make a difference together.

Your Membership Matters Convoy of Hope

A humanitarian, faith-based organization on a mission to feed the hungry and bring help and hope to communities in need. Through Disaster Services, Community Events, Agriculture, Women’s Empowerment, and Rural Initiatives, Convoy of Hope impacts lives globally, offering a helping hand where it’s needed the most.
Learn more about Convoy of Hope


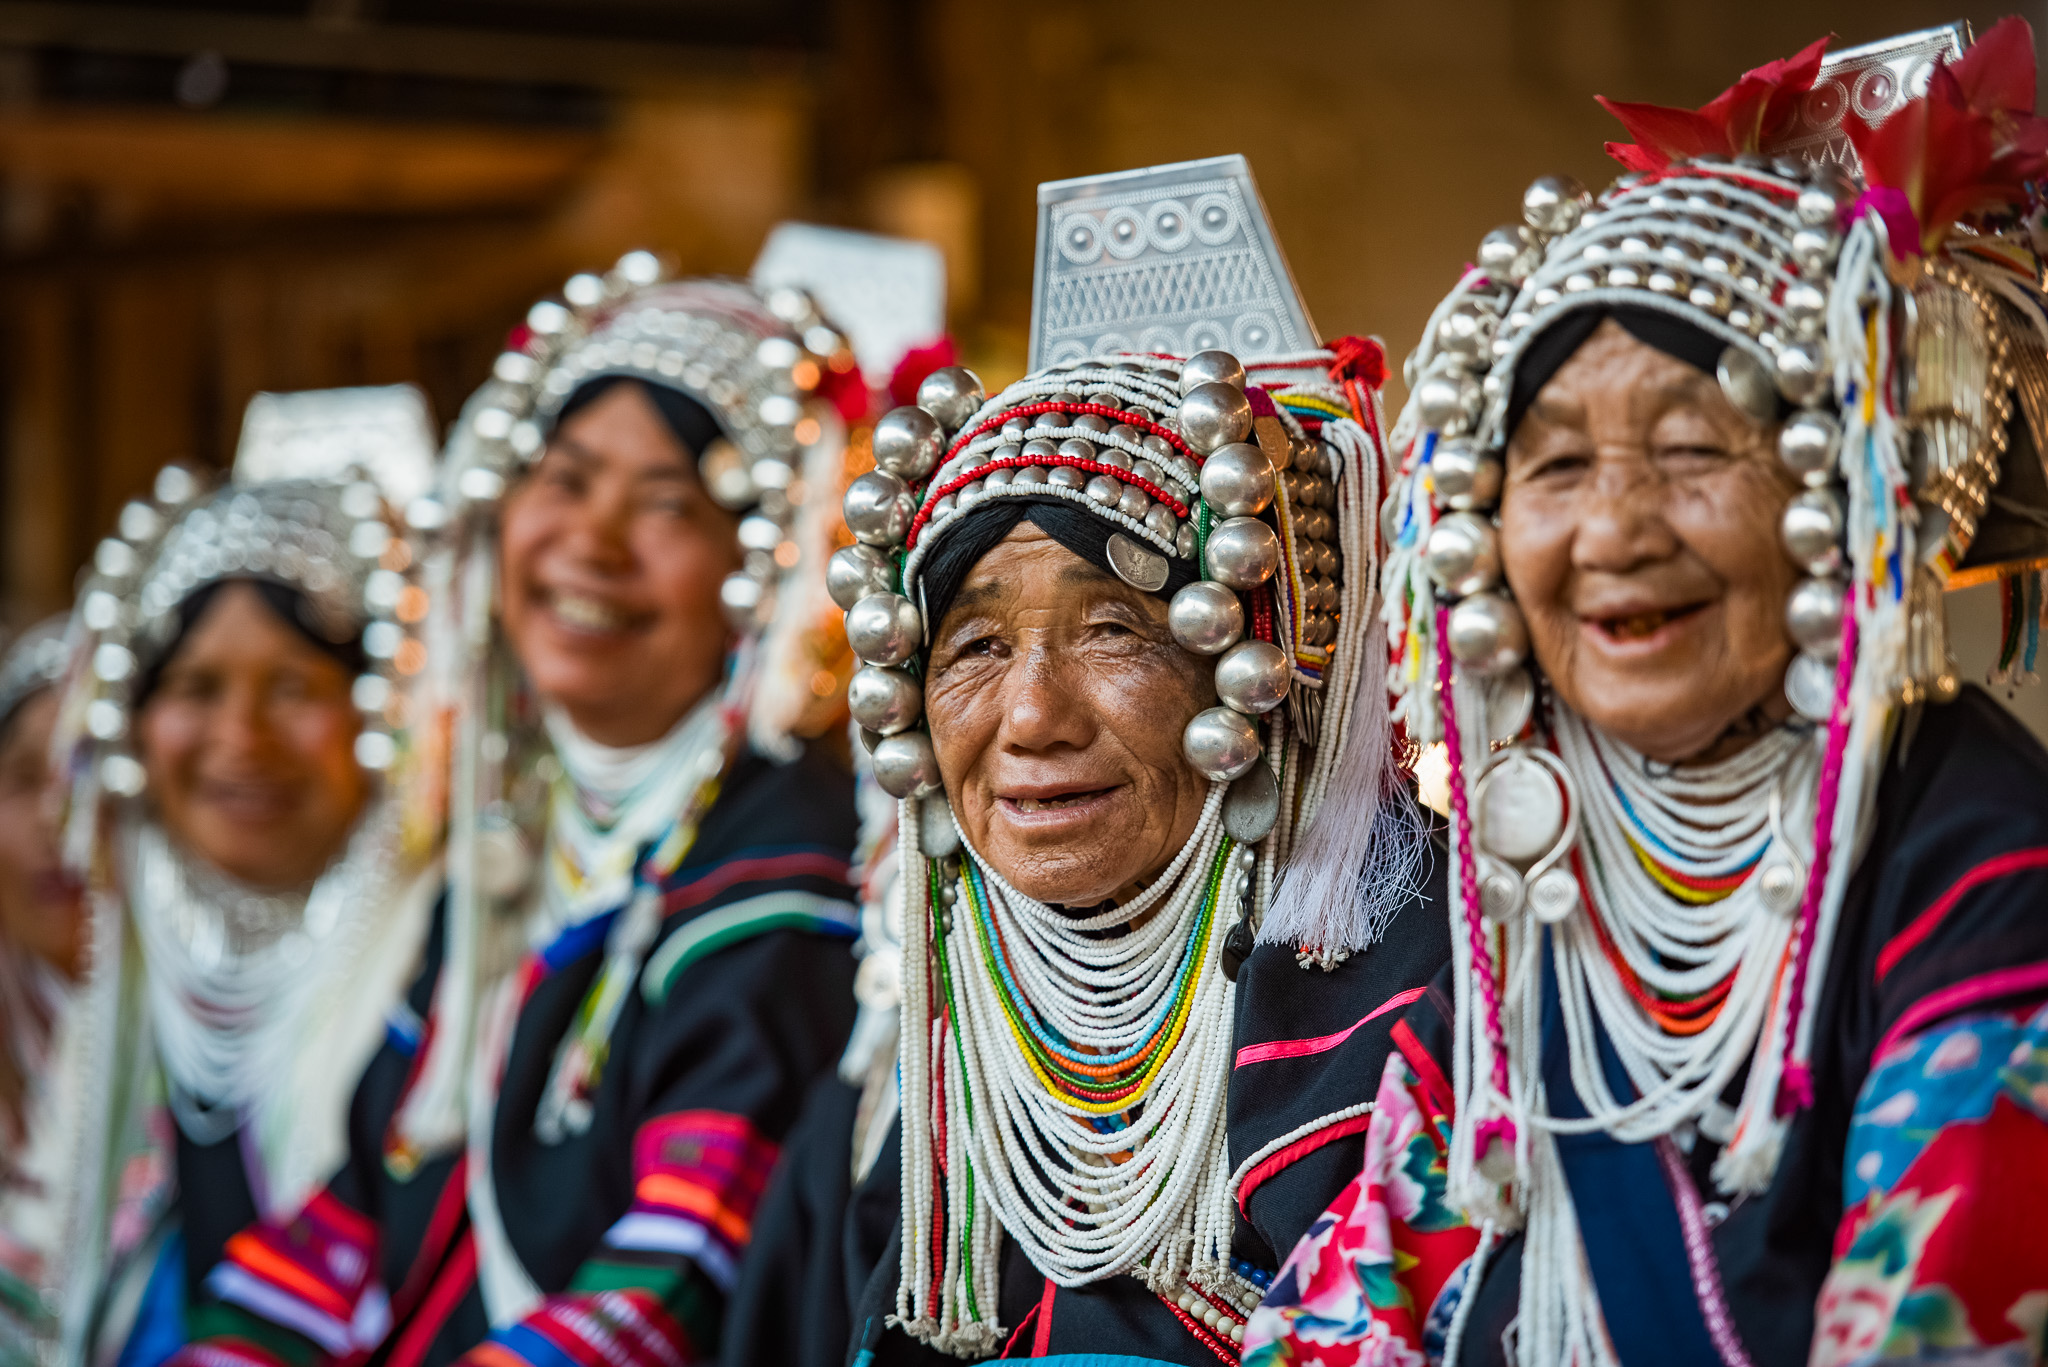
AG World MissionsPaa Daeng Akha village and AG Church with Pastor (woman) ??? In Northern Thailand.

Assemblies of God World Missions (AGWM) finds strength in your commitment to global missions. Your membership supports AGWM in reaching, planting, training, and serving worldwide. Together, we’ve seen countless lives transformed and churches planted, fulfilling the core values of the AG Fellowship. Every 54 seconds, someone comes to Christ, a testament to the impact your faith has globally.
Learn more about Assemblies of God World Missions (AGWM)


AG U.S. Missions

Your commitment to AGCU extends beyond borders, reaching communities within the United States through AG U.S. Missions. By supporting windows like Adult and Teen Challenge, Chaplaincy Ministries, and Intercultural Ministries, your membership becomes a beacon of hope, providing resources and encouragement where it’s needed most.
Learn more about Assemblies of God U.S. Missions 

Education: Nurturing Minds, Building Futures
Through AGCU, you’ve empowered educational initiatives, contributing to dozens of colleges, universities, public schools, and private Christian education. Your commitment to scholarship programs, educational materials, and financial education reflects a dedication to nurturing minds and shaping future leaders.

Project Rescue

Your membership takes a stand against human trafficking through support for Project Rescue. This multinational network fights to restore hope to survivors, and your involvement makes a significant impact in the ongoing battle against this global scourge.
Learn more about Project Rescue

YiPoA – Youth in Pursuit of Awakening
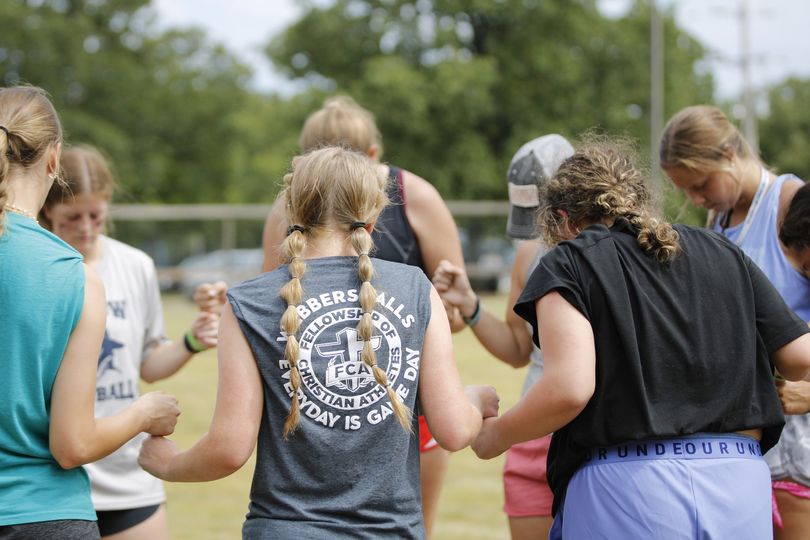
Your commitment to the Youth in Pursuit of Awakening (YiPoA) movement is a testament to your dedication to raising a generation that loves Jesus and lives out the gospel. Through events and programs, you’re actively participating in shaping future leaders who will impact the Kingdom.
Learn more about Youth in Pursuit of Awakening (YiPoA) 

Fellowship of Christian Athletes

With your membership, Fellowship of Christian Athletes (FCA) has the power to use the platform of sport to reach coaches and athletes with the transforming power of Jesus Christ. Your commitment to integrity, serving, teamwork, and excellence resonates through FCA’s mission to lead every coach and athlete into a growing relationship with Jesus Christ.
Learn more about Fellowship of Christian Athletes (FCA) 


REVFresh

Your benevolence through REVFresh refreshes ministry leaders, addressing personal needs and encouraging generous living. Your partnership supports a culture of support and care, reflecting the values of integrity, accountability, responsibility, and dedication.
Learn more about REVFresh


Springfield Giants

Your support of Springfield Giants Inc. signifies your commitment to character development through competition. The attributes of a Giant—character, accountability, responsibility, and dedication—are instilled in the youth, shaping them into confident future leaders.
Learn more about Springfield Giants


Simply Loved Orphan Care
Through Simply Loved Orphan Care, your membership contributes to projects and funding for orphanages in Eastern Europe. Your support ensures better care and preparation for life after the orphanage, reflecting your commitment to making a difference in the lives of these children.
Learn more about Simply Loved Orphan Care


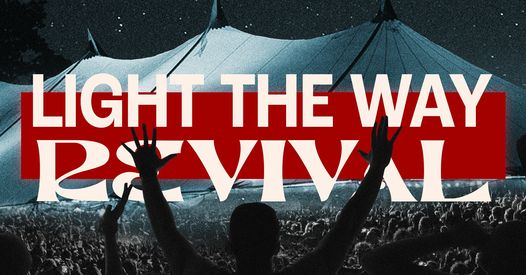
Light The Way Ministry
Your membership supports Light The Way Ministry, spreading the light and hope of Jesus Christ beyond the church walls. Through gatherings, events, and year-round efforts, your involvement becomes a source of transformation, bringing healings, deliverances, baptisms, salvations, and breakthroughs.
Learn more about Light The Way Ministry


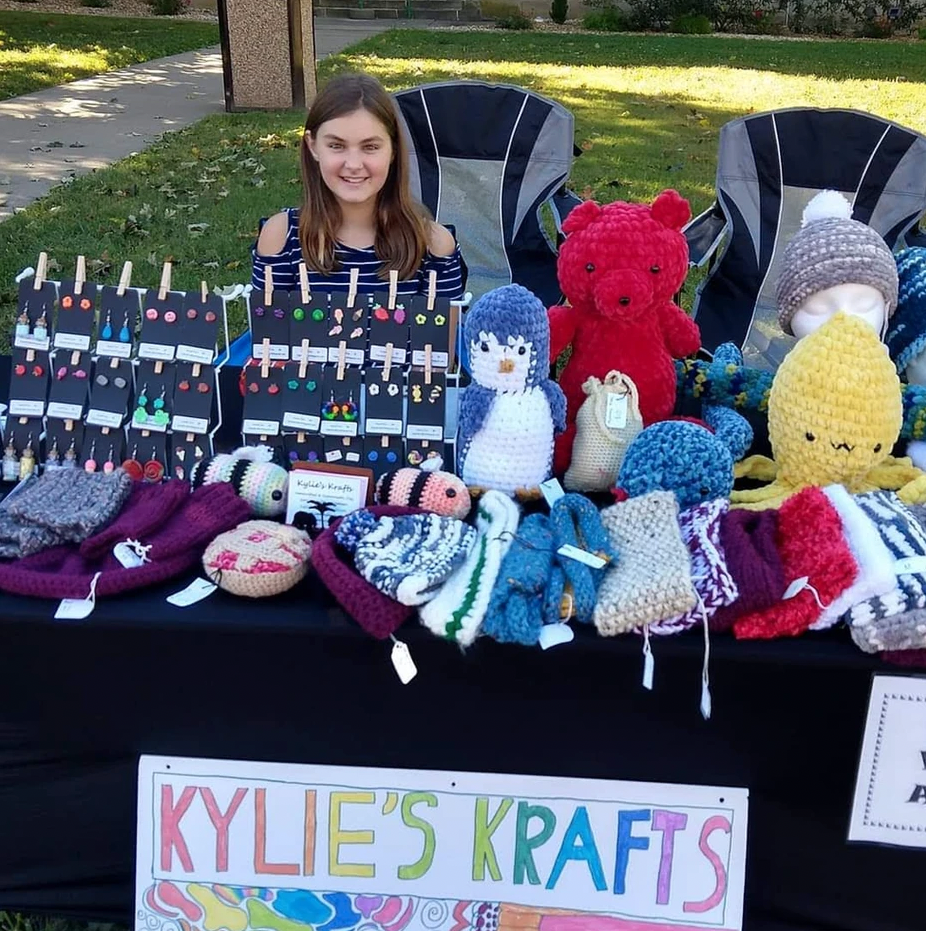
The Young Entrepreneurs Showcase
Your commitment to the Young Entrepreneurs Showcase provides a platform for young people to showcase their talents and entrepreneurial spirit. Through your support, you’re actively nurturing young minds and fostering a culture of innovation.
Learn more about Young Entrepreneurs Showcase

Banking With A Purpose

Much more than a catchphrase, our tagline is our passion, our reason why we do what we do. This is the impact of your membership with AGCU. Learn More About Banking with a Purpose

Like us on Facebook!

Scam Alert

Scam Alert

Scam Alert

Scammers are using the AGCU phone numbers to make calls. The caller claims to be with AGCU and is asking for personal and confidential information. AGCU’s phone number may show up on the caller ID, but the call is actually from a scammer, not AGCU. If you receive a call and the person asks for confidential information, hang up!

NEVER give out confidential information, such as account numbers, social security numbers, mother’s maiden name, or passwords to an unsolicited caller!

If you get a phone call, email, or a text message from AGCU or your credit card company, or anyone asking you to do something, pick up the phone and call AGCU’s Member Care team. Don’t call back to the number that sent you the text!

Learn more about spotting scams


AGCU Member Care services are just a call or click away. We’re proud to serve you and our community.

Call:
417-831-4398 or 866-508-AGCU (2428)
Monday-Friday 7:30 am- 5:00 pm CT

top 5 reasons to choose AGCU

TOP 5 REASONS TO CHOOSE AGCUTop 5 Reasons to Choose AGCU

Choosing your financial institution is an important decision. Banking with a Purpose means your faith is always in action. Your financial choices actively support missions, ministries, and humanitarian causes. It’s more than banking; it’s a faith-driven financial partnership. Here are the top five reasons to consider banking with AGCU:

Competitive Rates on Your Deposits

AGCU doesn’t just provide loans and savings accounts; we’re the folks that want your money to grow while you sleep. If you’re all about making your money pull double duty as it works hard for you AND the Kingdom, we’re right there with you. We’ve got checking accounts that can earn you as much as 2.5% APY, Jaw-dropping CD rates, and Money Market accounts that offer both flexibility of access and high earnings.

We’re All in This Together

AGCU shares your values and is committed to serving the Assemblies of God Church. But here’s the best part: when you bank with us, you’re not just managing your money; you’re part of something bigger. We donate a 10% of our earnings, like a tithe, to support ministries, humanitarian causes, and education. You’re not just banking; you’re investing in a faith-driven mission every time you choose AGCU.

We Get You

Financial alignment is essential, right? We understand the unique culture, ministry, and dreams of the Assemblies of God community. We’re here to help you achieve your goals. We get the challenges you face and are here to support and secure your financial journey, no matter how tricky it gets.

Your Money, Your Way

AGCU’s reach goes far and wide. As a member, you’re not confined to local branches. You have access to the extensive Shared Credit Union CO-OP network of over 30,000 ATMs and 5,000+ shared branches nationwide. That means more banking options and convenience wherever you go.

REASON 1A Faithful Legacy

AGCU has a rich history built on the call to serve its members. This legacy isn’t stuck in the past; it’s a living testament that will be felt for generations. We hold fast to Godly principles, ensuring that every member is part of a legacy rooted in faith and dedicated to serving the Assemblies of God community.

In a nutshell, AGCU – Assemblies of God Credit Union offers much more than just banking; it offers a faith-infused financial partnership with a purpose. It’s your money, your faith, and your values working together to create a better future for you and the world. Join us, and let’s make a difference, one deposit at a time.

Join AGCU today!

To become a member of AGCU, either start a Video Banking Call or apply through an online application.


Start a Call Video Banking
Speak face-to-face with an AGCU Video Banking Representative from anywhere.
Give it a try today! Video Banking Hours (CST): Mon – Fri: 9:00 a.m.- 5:00 p.m.


Apply through online application.


Do you have questions regarding becoming a member or opening an account? Call (417) 831-4398 or fill out our contact form and we will contact you!


Banking With A Purpose

Much more than a catchphrase, our tagline is our passion, our reason why we do what we do. This is the impact of your membership with AGCU. Learn More About Banking with a Purpose

Like us on Facebook!

APY=Annual Percentage Yield