Ministry & Business Savings
Ministry & Business
Certificates of Deposit
Put your organization’s reserves and excess cash to work with a predictable return for a set amount of time.
View Current CD Rates
Contact AGCU
Make More of the Money Your Organization Has Set Aside
Not every dollar your business or ministry holds needs to sit in a checking account. If you have funds you don’t expect to use right away, an AGCU business certificate of deposit can help those reserves earn a predictable return.
A ministry & business CD holds a set amount of money for a specific term while earning dividends at a fixed rate. It can be a useful option for businesses that want to earn more on funds they can comfortably set aside.
The basic idea: Keep the cash you need for daily operations accessible. Put money you won’t need immediately into a CD and let it earn until maturity.
Why Choose an AGCU Ministry and Business Business CD?
Predictable Earnings
Lock in your rate for the certificate term so you know how your business funds will earn.
Put Reserves to Work
Earn dividends on cash your business has set aside for future needs instead of leaving all of it in a transactional account.
Multiple Term Options
Choose from available certificate terms to match your business plans and cash-flow timeline.
Federally Insured
Qualifying deposits are federally insured by the National Credit Union Administration (NCUA) up to applicable limits.
Monthly Dividends
Dividends on AGCU certificates are paid monthly.
Banking with a Purpose
Your deposits help AGCU provide financial resources to businesses, churches, ministries and members.
The Basics
How Does a Ministry & Business CD Work?
1
Choose an Amount
AGCU CDs have a minimum opening deposit of $1,000.
2
Choose a Term
Select from available certificate terms based on when your organization may need the funds.
3
Earn Dividends
Your funds earn the disclosed rate during the certificate term.
4
Reach Maturity
When the term ends, review your options and decide what your organization needs next.
Plan Before You Deposit
Protect Your Organization Cash Flow
A competitive rate is valuable, but access to cash matters too.
Before moving funds into a CD, consider upcoming payroll, taxes, vendor payments, planned purchases and an appropriate cash reserve for unexpected expenses.
A CD is best suited for funds your business can reasonably leave on deposit until maturity. An early withdrawal penalty may apply if principal is withdrawn before the certificate matures.
Choosing a Business Savings Account
Ministry & Business CD or Money Market?
Both can help your business earn dividends on money you’re not using for everyday operations. The biggest difference is how readily you need to access the funds.
Ministry & Business CD
Designed for funds your organization can leave on deposit for a specific term while earning a predictable return.
Think: longer-term reserves, future projects or funds with a known timeline.
Ministry & Business Money Market
Designed for organization savings that need greater accessibility while still earning dividends.
Think: operating reserves and savings you may need to access.
Learn About Ministry & Business Money Markets →
Business Savings Strategy
Consider a CD Ladder for Organization Reserves
Your organization doesn’t necessarily have to choose between locking up all of its savings and keeping all of it immediately accessible.
A CD ladder divides funds among several certificates with different maturity dates. As each CD matures, your business can use the funds or reinvest them into another certificate.
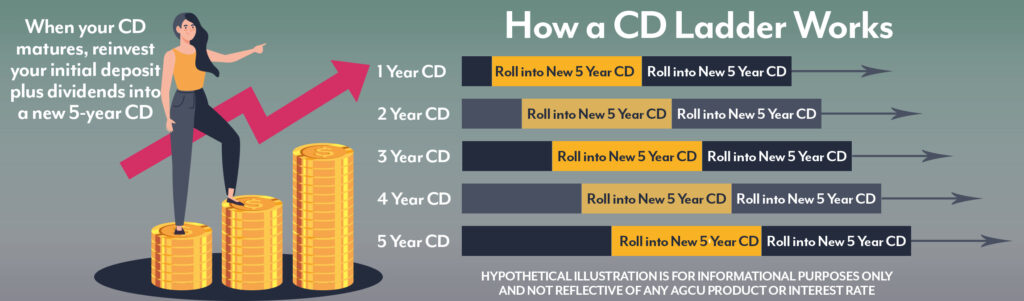
Why use a CD ladder? Staggered maturity dates can help an organization balance predictable earnings with more regular opportunities to access part of its reserves.
At the End of Your Term
What Happens When Your Ministry & Business CD Matures?
Your CD’s maturity date is the end of its agreed-upon term. At AGCU, certificates automatically renew unless you choose another option.
Good to Know
You Have a 10-Day Grace Period
After your CD matures, you have a 10-calendar-day grace period to make changes or withdraw funds without an early withdrawal penalty.
Your Business Has Options
Renew the CD
Keep the funds in a certificate and continue earning dividends. Review current rates and available terms before maturity.
Move the Funds
Move some or all of the funds into another AGCU business account if your cash-flow needs have changed.
Withdraw the Funds
Withdraw some or all of the funds during the grace period without an early withdrawal penalty.
If you take no action, your certificate will automatically renew according to the terms of your account. The rate at renewal may be different from the rate earned during the previous term.
Another Way Your CD Can Work for Your ORGANIZATION
Need Funds Before Your CD Matures?
Depending on your needs and eligibility, your organization may be able to use an AGCU CD as collateral for a share secured loan rather than withdrawing the certificate early.
Your CD stays on deposit and continues earning dividends while the loan is repaid.
Learn About Share & CD Secured Loans
Business Savings
Put Your Organization Reserves to Work
Start with as little as $1,000 and choose from available AGCU certificate terms and rates.
View Current CD Rates
Talk With AGCU
Banking with a Purpose.
APY = Annual Percentage Yield. Minimum opening deposit and certificate terms may vary by product or promotion. An early withdrawal penalty may apply. Rates and terms are subject to change. Membership eligibility requirements apply. Federally insured by NCUA.