Understanding AGCUโ€™s Funds Availability Policy for ATM Deposits

Funds Availability Policy for ATM Deposits
AGCU is committed to serving your financial needs while ensuring the safety and reliability of your funds. To better protect your account and align with industry best practices, weโ€™re updating our Funds Availability Policy for check deposits made at ATMs.ย  Checks deposited at ATMs will be subject to a standard 2-business-day hold. However, Treasury and cashierโ€™s checks will be available the next business day, per federal regulations.

We understand this policy change may raise questions, so weโ€™ve outlined key details below to help you understand why this adjustment is necessary and how it benefits you.

What Is a Funds Availability Hold?

When you deposit a check at an ATM, the funds are credited to your account immediately; however, this does not mean they are immediately available for withdrawal or use. A funds availability hold delays access to the deposited amount until the check can be reviewed and validated.

Why Are Funds Availability Holds Necessary?

Placing a temporary hold on check deposits serves several important purposes:

  • Fraud Prevention:ย Holds allow us time to validate the authenticity of a check, helping to protect you from fraud or losses due to counterfeit or invalid checks.
  • Avoiding Returned Checks:ย If a check you deposit is returned unpaid, the amount is deducted from your account. A hold period reduces the risk of fees or negative balances caused by returned checks.
  • Mitigating Losses:ย This practice is a standard measure in the financial industry to ensure responsible account management and to safeguard membersโ€™ funds.

When Will My Funds Be Available?

Hereโ€™s a breakdown of our updated policy:

  • Standard Check Deposits:ย Funds from checks deposited at AGCU ATMs will generally be available on theย second business dayย after the deposit.
  • Treasury and Cashierโ€™s Checks:ย These deposits will be available on theย next business day, in compliance with federal regulations.
  • Partial Availability:ย A portion of the deposit, at least $225,ย mayย be available immediately or on the first business day after the deposit.

How Can I Access My Available Balance?

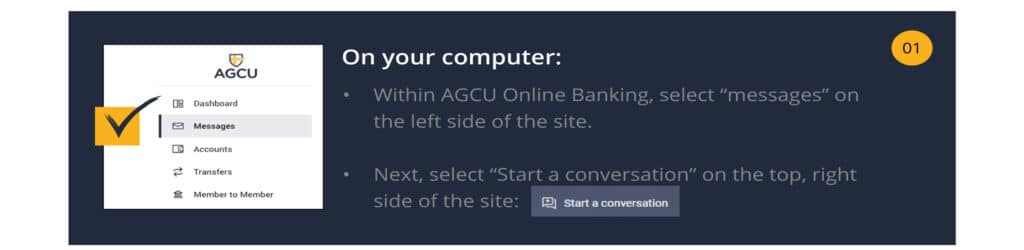
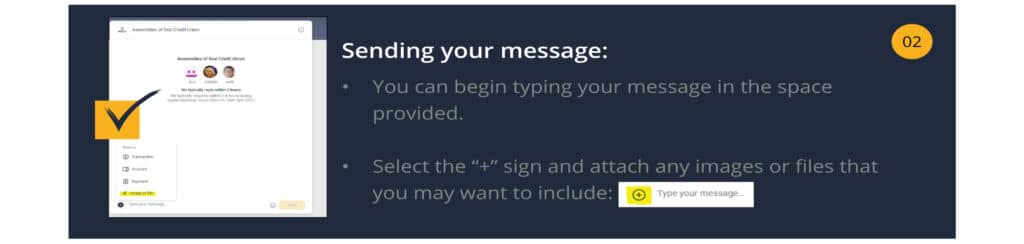
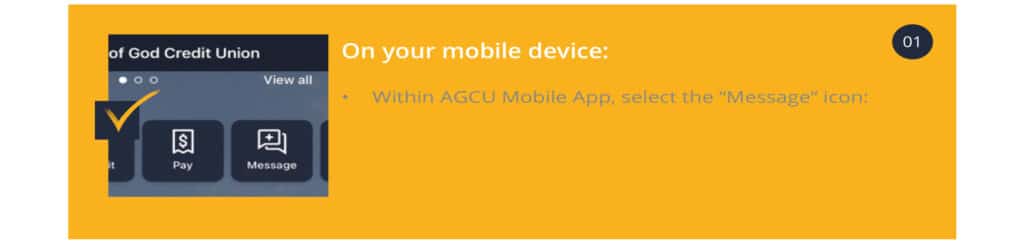
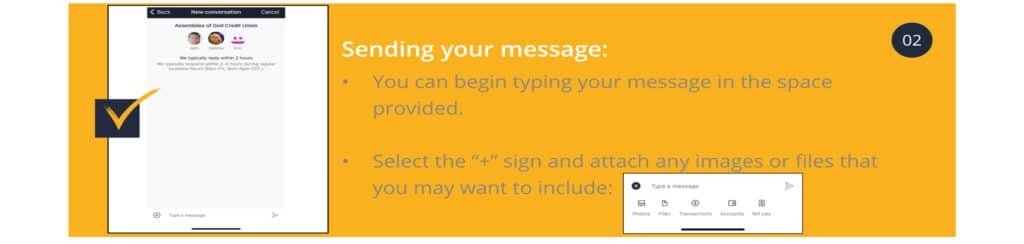
To check your available balance at any time:

What If I Need Funds Sooner?

We understand that unexpected financial needs can arise. If you need access to funds before the hold period ends, please reach out to a Member Care representative. In some cases, we may be able to expedite the availability of funds.

How to Manage Funds for Better Access

Here are a few tips to help you plan deposits and access funds more efficiently:

  1. Direct Deposit:ย Electronic deposits are often available immediately. Consider setting up direct deposit for regular payments like paychecks or Social Security benefits.
  2. Mobile Deposit:ย Using AGCUโ€™s mobile app, you can deposit checks conveniently from your phone and may see funds released faster than ATM deposits.
  3. Branch Deposits:ย Depositing checks in person at an AGCU branch allows for immediate processing and may provide quicker availability.
  4. Overdraft Protection:ย Linking a savings account or overdraft line of credit can ensure you have funds available if you need them.

AGCU is committed to providing secure, accessible, and faith-centered financial solutions. Our Funds Availability Policy ensures your deposits are handled responsibly, protecting you and your account from potential risks.

For more details about our updated policy, feel free to review your account documentsย or speak with an AGCU representative.

Banking With A Purpose

Much more than a catchphrase, our tagline is our passion, our reason why we do what we do. This is the impact of your membership with AGCU.ย Learn More About Banking with a Purpose

Like us on Facebook!

ย 

Banks vs. Credit Unions: Whatโ€™s the Difference and Why AGCU Might Be Right for You!

Banks vs. Credit Unions: Whatโ€™s the Difference?

Understanding how financial institutions work can help you choose the one that best fits your needsโ€”and your values.

When it comes to managing your finances, choosing the right financial institution can make a meaningful difference.

Banks and credit unions offer many of the same services. But how they operateโ€”and who they serveโ€”sets them apart. Letโ€™s take a closer look.

Banks vs Credit Unions

Banks vs. Credit Unions: Key Differences

Ownership and Purpose

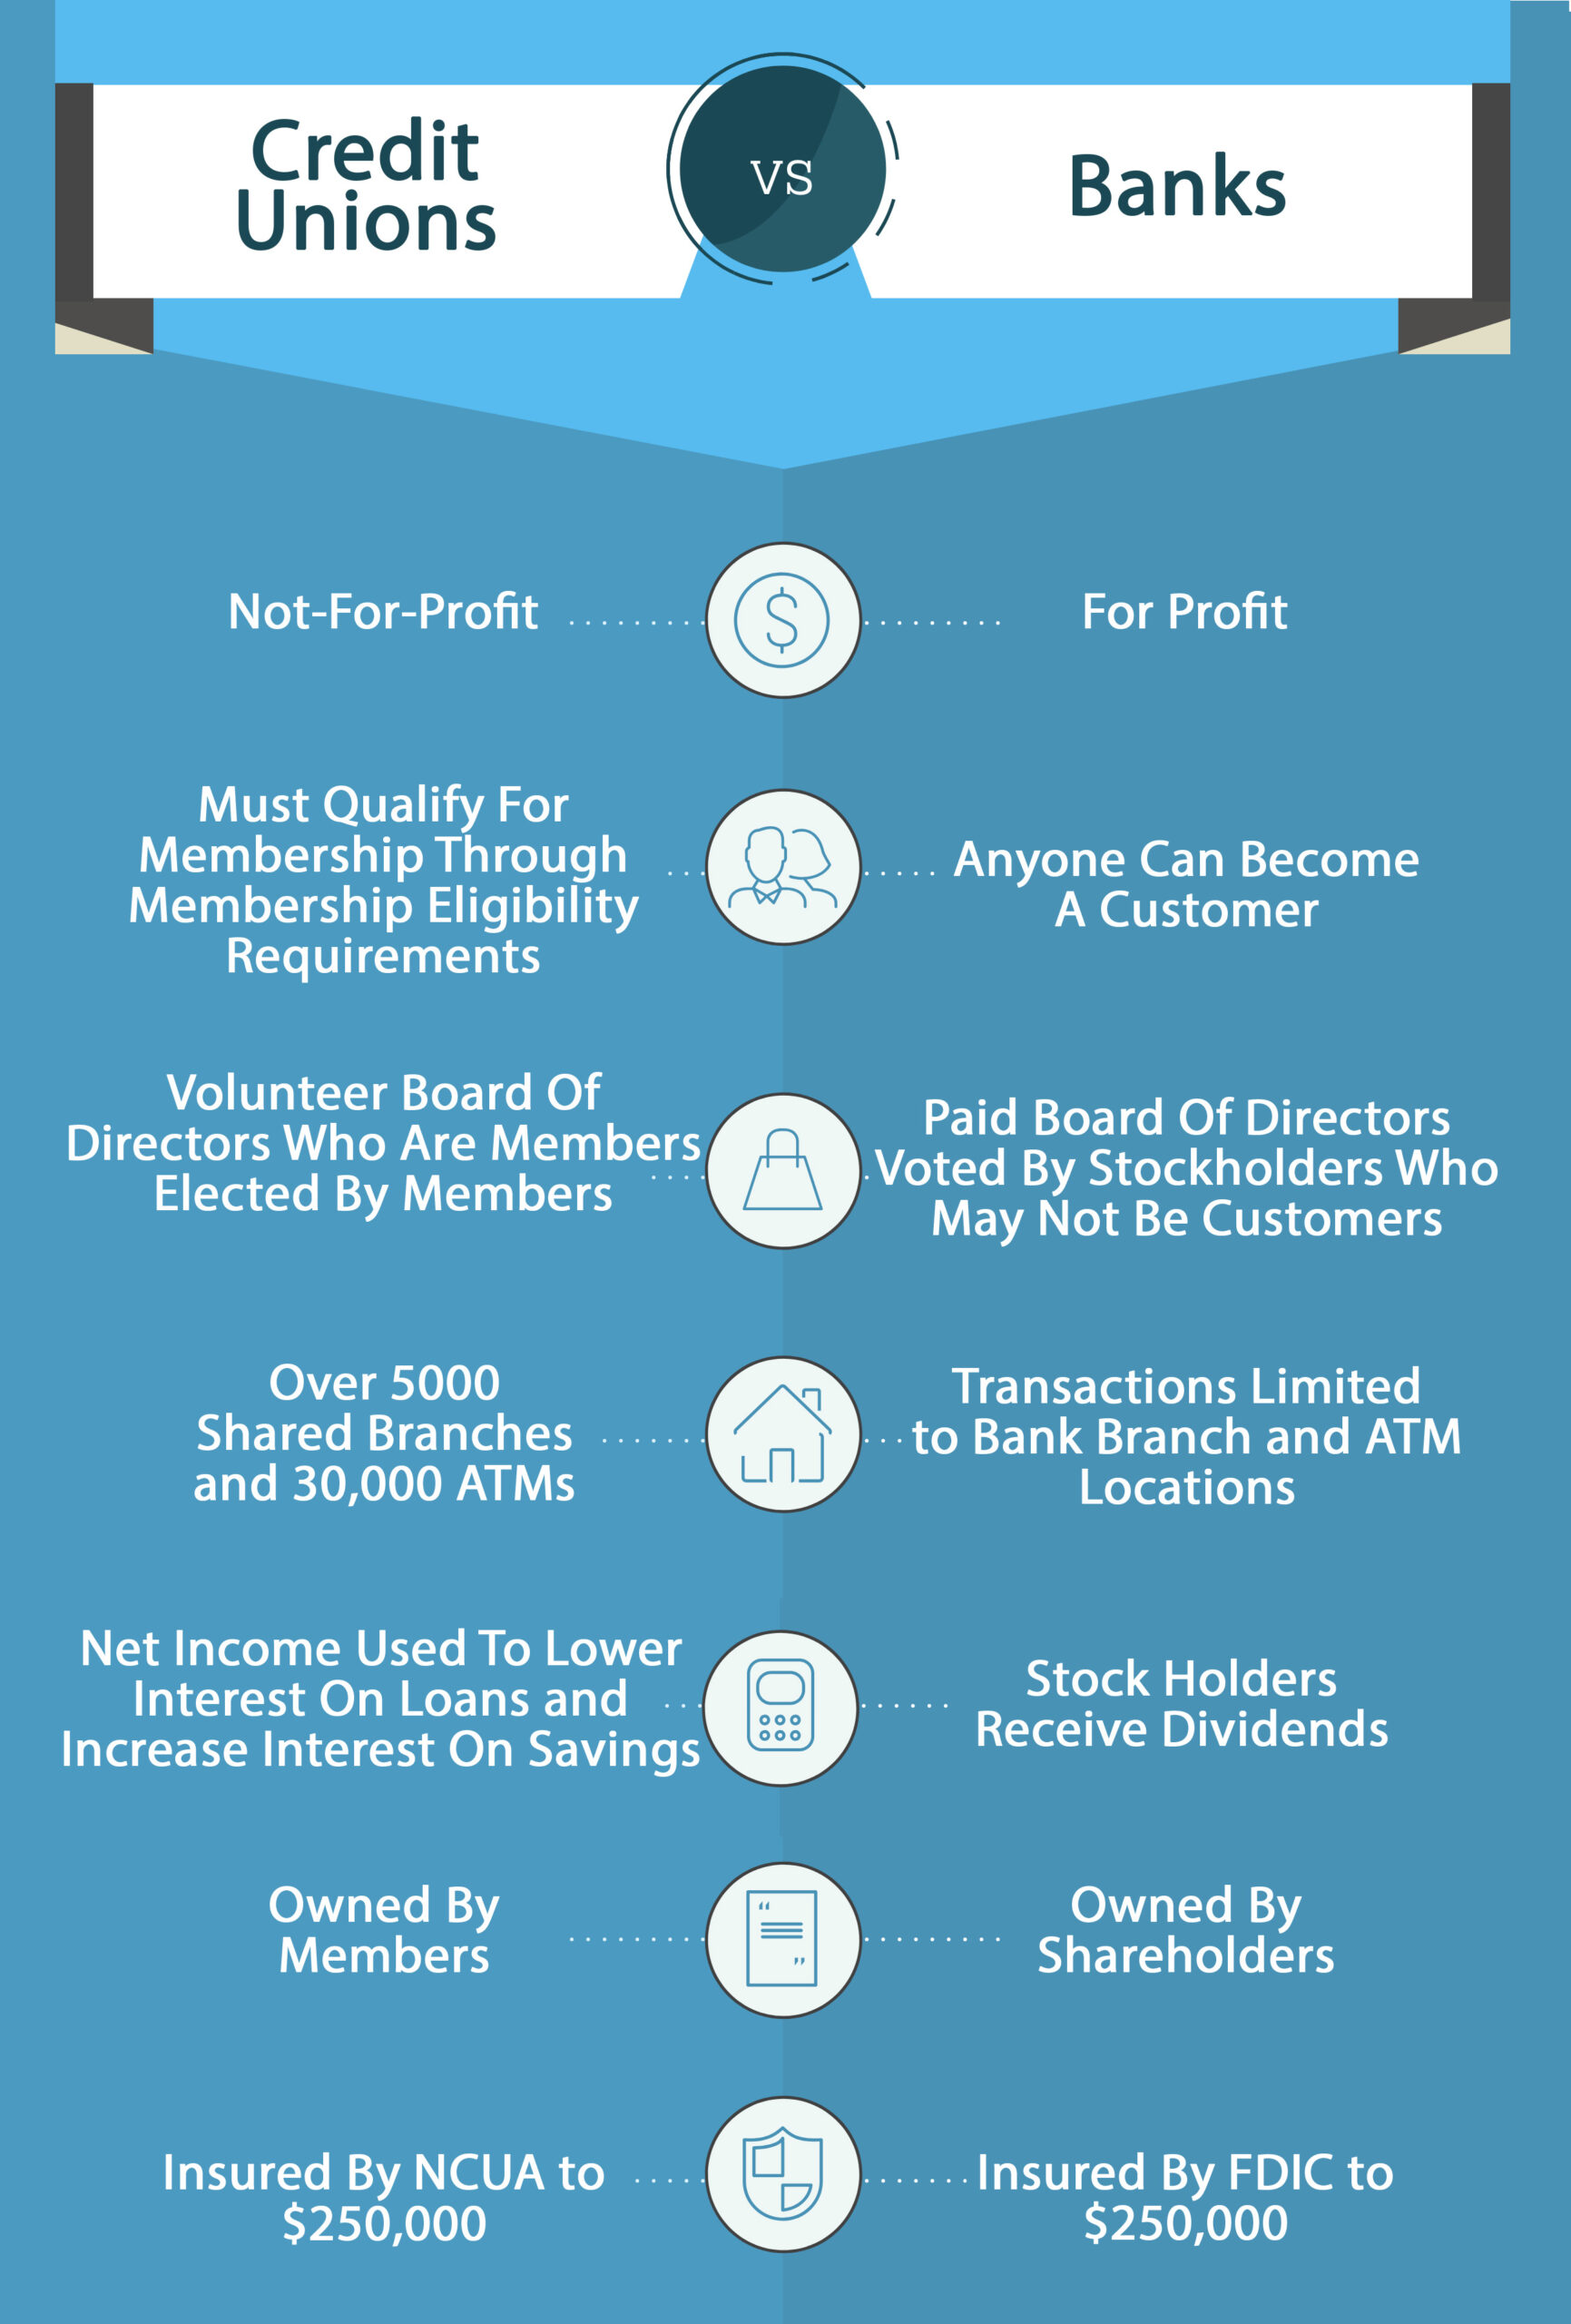
Banks are for-profit institutions owned by shareholders. Their primary goal is to generate profit, which is returned to shareholders as dividends.

Credit unions, on the other hand, are not-for-profit organizations owned by their members. When you join a credit union, youโ€™re not just a customerโ€”youโ€™re an owner.

Credit unions may have membership requirements based on where you live, work, or worship. These requirements help maintain a shared connection among members.

As a credit union, AGCU is committed to serving our members and the Assemblies of God by offering financial solutions that reflect shared faith and community values.

12 Steps to Financial Wellness-Step 1: How to Track Your Spending

12 Steps to Financial Wellness

Step 1: Track Your Spending

Gain a clearer understanding of where your money goes and begin building the awareness needed to make confident financial decisions.

Your Financial Wellness Journey Step 1 of 12

Are you ready to begin a journey toward greater financial wellness? Throughout this series, AGCU will explore 12 practical steps designed to help you better understand your finances, strengthen your habits and make more informed decisions.

The first step is learning where your money is actually going. Tracking your spending gives you an honest picture of your financial habits and provides the foundation for creating a realistic budget, reducing debt and reaching your goals.

1

Choose a Tracking Method

Tracing every dollar can seem overwhelming at first, but the right method can make the process much easier. Choose an approach that fits naturally into your routine and that you will use consistently.

AGCU Online Banking

AGCU members can review transactions and use built-in financial tools within Online Banking. Log in through the AGCU web portal and explore the available money-management features.

Budgeting App

A budgeting app can organize transactions, assign purchases to categories and help you monitor spending throughout the month. Review privacy policies and any subscription costs before choosing an app.

Spreadsheet

A spreadsheet is a useful choice if you prefer to see your information clearly in rows and categories. Record each purchase and update your totals regularly.

Envelope System

If you frequently use cash, divide your available spending money into envelopes for categories such as groceries, entertainment and personal spending.

Receipt Method

Save every receipt during the month. At the end of each week or month, review the receipts and sort each purchase into the appropriate spending category.

Pencil and Paper

A notebook or printed tracking sheet can be simple and effective. Keep it somewhere convenient and write down purchases as soon as possible.

2

Review Your Accounts Carefully

Along with your chosen tracking method, review your checking account, debit card and credit card activity regularly. Do not rely entirely on memoryโ€”many everyday expenses are easy to overlook.

Look carefully for:

  • Recurring subscriptions and automatic renewals
  • Streaming, software and mobile app charges
  • Impulse purchases and convenience spending
  • Duplicate or incorrect transactions
  • Fees or interest charges
  • Purchases you had forgotten about
  • Transactions you do not recognize

Reviewing your accounts does more than help you track spending. It can also help you identify errors or possible fraudulent activity more quickly.

3

Review and Categorize Your Purchases

At the end of each week or month, organize your purchases into categories. This helps you see how much of your income is going toward necessities, financial goals and flexible spending.

Category Examples
Housing Rent, mortgage, utilities, repairs and insurance
Transportation Vehicle payments, fuel, insurance, maintenance and transit
Food Groceries, restaurants, takeout, coffee and snacks
Debt Payments Credit cards, personal loans, student loans and medical debt
Savings Emergency savings, retirement and short-term goals
Personal Spending Shopping, entertainment, hobbies and subscriptions
Giving Tithes, charitable gifts and community support

Remember to include automatic payments that may be easy to forget, such as insurance premiums, memberships, cloud storage, streaming services and annual app renewals.

Try the 7-Day Spending Challenge

For the next seven days, record every dollar you spend. Include cash, debit card purchases, credit card transactions, tips, subscriptions and automatic payments.

At the end of the week, review the list and ask yourself: Does my spending reflect what matters most to me?

What Should You Look For?

After you have tracked and categorized your purchases, review your results for patterns.

  • Categories where you consistently spend more than expected
  • Subscriptions or services you no longer use
  • Frequent small purchases that add up over time
  • Expenses that could be reduced without affecting your priorities
  • Areas where your spending already aligns well with your goals

You do not need to eliminate every nonessential expense. The purpose is to make thoughtful choices and ensure your money is supporting the life and priorities that matter to you.

See Your Finances More Clearly

AGCU Online Banking makes it easier to review account activity, monitor transactions and stay connected to your finances wherever you are.

Log In to Online Banking Explore Digital Banking
Important: This article is provided for general educational purposes and is not financial, legal, credit or tax advice. Features and availability within Online Banking may change. Membership eligibility applies. Federally insured by NCUA.

Components of a Car Payment

When you get a loan to buy a car, youโ€™ll get a new set of keys โ€” and a new monthly payment. You may be wondering how this payment is determined and calculated. 

So many questions, and weโ€™ve got answers! Letโ€™s break down the parts of a car payment, explain how monthly payments are calculated, and offer tips for managing your expenses well. 

Components of a Car Payment

1. Principal
This is the amount you borrow to purchase your car. For example, if the car costs $35,000 and you make a $5,000 down payment, your loan principal is $30,000. Each monthly payment chips away at this amount, with a portion dedicated to reducing your loan balance. Paying extra toward the principal can help you pay off the loan faster.

2. Interest
Interest is the cost of borrowing money and is calculated as a percentage of your principal. Your interest rate depends on factors like your credit score, loan term, and market conditions. The lower your rate, the less youโ€™ll pay over time.

3. Loan Term
The loan term is how long youโ€™ll take to repay your loan, typically expressed in months (e.g., 36, 60, or 72 months). A longer term means lower monthly payments but higher total interest costs over the life of the loan.

4. Taxes and Fees
If you roll upfront costs like taxes, registration, or fees into your loan, theyโ€™ll increase your principal and, consequently, your monthly payment.

5. Add-ons
Optional extras like extended warranties or gap insurance can also be financed, raising your monthly payment.


Whatโ€™s Not in Your Payment (But Still Important)

Owning a car comes with additional costs that arenโ€™t included in your loan payment but need to be part of your budget:

  • Insurance: Comprehensive and collision coverage are often required by lenders. Shop for the best rates to save money.
  • Maintenance: Budget for regular servicing to keep your car in good condition.
  • Fuel/Electricity: Whether gas-powered or electric, your car needs energy to get you from point A to point B.

How Car Loan Payments Are Calculated

When a lender calculates your monthly payment, they consider:

  • The price of the car, minus any down payment or trade-in value
  • The loan principal (including add-ons and rolled-in costs)
  • The interest rate
  • The loan term (number of months)

They then divide the total loan cost (principal + interest) by the number of months in the loan term to determine your monthly payment.


Tips for Managing Your Car Payment

1. Shop Around for the Best Loan
Get the vehicle you want at a rate you can afford with AGCU. Contact an AGCU lender to secure the best interest rate and terms. Even a slight difference in the rate can save you a lot over the life of the loan.

2. Make a Larger Down Payment
A bigger down payment reduces the amount you need to finance, lowering your monthly payments and the total interest paid.

3. Opt for a Shorter Loan Term
While shorter terms come with higher monthly payments, they also mean less interest over the life of the loan. If your budget allows, choosing a shorter term can save you money in the long run.

4. Set a Budget for Ownership Costs
Remember to account for insurance, maintenance, and fuel when calculating your total car expenses each month.


Final Thoughts

Understanding the anatomy of your car payment can empower you to make smarter decisions about financing and managing your loan. If youโ€™re ready to take control, consider opening an interest-earning savings account to build your down payment or plan for unexpected costs.
Have a question or want to get started with an application? Connect with an AGCU Video Banking Representative or apply online today!

Or you can speak face-to-face with an AGCU Video Banking Representative from anywhere.
Give it a try today! Video Banking Hours (CST): Mon โ€“ Fri: 9:00 a.m.- 5:00 p.m.

Disclaimer: Always consult a financial advisor, accountant, or lawyer to discuss your specific situation.

Banking With A Purpose

Much more than a catchphrase, our tagline is our passion, our reason why we do what we do. This is the impact of your membership with AGCU.
Learn More About Banking with a Purpose
More articles

Like us on Facebook!

5 Best Times to Buy a Car: Your Guide to Scoring the Best Deals

5 best times to buy a car

A little planning goes a long way. Here’s when to shop, when to wait, and how to walk into the dealership with confidence.

Buying a car is one of the biggest financial decisions you’ll make, and the price you pay has a lot to do with when you show up. Dealers operate on sales cycles, quotas, and inventory pressures that create real windows of opportunity for smart buyers.

Before heading to the lot, be sure to check AGCU’s auto loan rates and apply for pre-approval online. Walking in pre-approved gives you real negotiating power.

1. The Best Days to Buy: Skip the Weekend Rush

If you’ve ever visited a dealership on a Saturday, you know the feeling: packed showrooms, distracted salespeople, and very little motivation for anyone to cut you a deal.

Instead, try heading in on a Tuesday or Wednesday. Foot traffic is lighter, salespeople have more time to focus on you, and the quieter atmosphere creates more room for negotiation.

Quick tips for your visit:
  • Aim for midweek whenever your schedule allows
  • Call ahead to confirm inventory
  • Take your time and avoid pressure decisions

2. The Best Time of Day: Afternoon Has Its Advantages

Late afternoon (4โ€“6 PM) tends to be a sweet spot for buyers. Salespeople who haven’t closed a deal yet may be more motivated before closing time.

A motivated salesperson and a patient buyer can be a great combinationโ€”just be ready to walk away if the deal doesnโ€™t feel right.

3. The Best Months to Buy: September, October & December

Timing your purchase to the right month can significantly affect the price you pay.

September and October are great for current-year models as new inventory arrives. December is often the best month because dealers are racing to meet annual sales goals.

The final week of the yearโ€”especially December 26โ€“31โ€”often produces the deepest discounts.

4. The Best Time of the Month: The Last Few Days

Dealership sales quotas reset each month. As the final days approach, the urgency to hit targets increases.

Shopping during the last three to five days of the month can give you additional negotiating power.

5. Best Time to Buy Used: January and February

The new year often brings a surge of trade-ins after holiday purchases.

Dealerships typically have more used inventory than they want to hold, which means stronger motivation to sell at competitive prices.

Worst Times to Buy a Car

  • Weekends: Higher buyer traffic means less negotiation leverage.
  • Early in the Year: Discounts tend to be smaller than later months.
  • Summer: Generally fewer incentives unless tied to a holiday event.

Frequently Asked Questions

What is the best month to buy a car?
December often provides the deepest discounts, followed by September and October.

Is it better to buy at the end of the month?
Yes. Dealers are more motivated to hit sales quotas.

What day of the week is best?
Tuesday and Wednesday typically provide a calmer environment for negotiation.

Should I get pre-approved?
Absolutely. Pre-approval strengthens your negotiating position.

Make Your Move With AGCU

AGCU offers competitive rates on new and used vehicle loansโ€”including 100% financing options.

Your next steps:

The right car at the right price is out thereโ€”and with the right timing, you’ll be ready to find it.

20 Back-to-School Hacks So You Can Beat Inflation

“`html id=”bts20hacks”

20 Back-to-School Hacks to Beat Inflation

Smart Ways to Stretch Your Back-to-School Budget

Back-to-school shopping has become more expensive in recent years, but that doesn’t mean you have to overspend. With a little planning and a few smart shopping strategies, you can save money while making sure your students have everything they need for a successful school year.

Here are 20 practical ways to beat inflation and keep more money in your pocket.

20 Back-to-School Hacks to Beat Inflation

20 Money-Saving Hacks

1. Shop Your House First

Before buying anything new, check closets, drawers, and last year’s backpacks for reusable supplies.

2. Wait for the Official Supply List

Buying too early can lead to unnecessary purchases that your child’s teacher may not require.

3. Set a Budget

Decide how much you’re willing to spend before you start shopping.

4. Compare Prices

Check multiple stores and compare online prices before making larger purchases.

5. Buy Store Brands

Generic notebooks, folders, and pencils often perform just as well as name brands.

6. Buy in Bulk

Split larger packages with another family to save money on commonly used supplies.

7. Shop Tax-Free Weekends

If your state offers a tax holiday, plan your shopping around those dates.

8. Reuse Backpacks & Lunch Boxes

A quick cleaning may save you from buying new ones every year.

9. Skip Trendy Extras

Character notebooks and designer supplies may be funโ€”but they also cost more.

10. Shop Clearance Sections

Many stores continue discounting school supplies after the season begins.

11. Buy Clothes in Stages

Students don’t need an entire wardrobe on the first day of school.

12. Watch for Student Discounts

Many retailers offer discounts on laptops, software, and technology for students.

13. Pack Lunch More Often

Bringing lunch even a few days each week can add up to significant savings over the school year.

14. Label Everything

Prevent expensive replacements by labeling backpacks, lunch boxes, and supplies.

15. Budget for Hidden Costs

Remember activity fees, sports, field trips, fundraisers, and classroom donations.

16. Avoid Impulse Purchases

Those small checkout items can quickly push you over budget.

17. Shop With Cash or a Spending Limit

Having a limit makes it easier to avoid overspending.

18. Track Spending in Digital Banking

Use AGCU Online Banking or Mobile Banking to monitor purchases and stay on budget.

19. Start Saving for Next Year Today

Setting aside a small amount each month makes next year’s shopping much less stressful.

20. Focus on What Really Matters

Kids remember great teachers, friends, and experiencesโ€”not whether every notebook was brand new.

๐Ÿ’ก Money-Saving Tip

Saving just $5 on ten different purchases adds up to $50โ€”and those small savings can make a big difference during back-to-school season.


Back-to-School Shopping Checklist

  • โ˜ Inventory last year’s supplies
  • โ˜ Create a shopping list
  • โ˜ Compare prices
  • โ˜ Use coupons and sales
  • โ˜ Set a spending limit
  • โ˜ Track purchases
  • โ˜ Save receipts
  • โ˜ Budget for hidden school expenses

Final Thought

Inflation may make back-to-school shopping more expensive, but smart planning can help you keep costs under control.

By shopping strategically, avoiding impulse purchases, and using AGCU’s digital banking tools to track your spending, you can start the school year preparedโ€”and keep your budget on track.