AGCU Annual Business Meeting

2025 AGCU’s Annual Business Meeting 5pm Thursday, June 19 at Central Assembly of God 1301 N Boonville Ave, Springfield, MO 65802

Join Us for AGCU’s Annual Business Meeting – 5pm, June 19 at Central Assembly of God 1301 N Boonville Ave, Springfield, MO 65802

We’re inviting all AGCU members to be a part of something that matters: our Annual Business Meeting, taking place on Thursday, June 19 at 5 p.m. at Central Assembly of God, 1301 N Boonville Ave, Springfield, MO.

This is your opportunity to vote for board members, celebrate AGCU’s accomplishments over the past year, and help chart the course for our future. Together, we’ll make important decisions that impact our members, our mission, and the communities we serve.

Come early! Hors d’oeuvres will be served starting at 4:00 p.m.

As a special thank you, the first 75 voting members who RSVP and attend will receive a $20 gift card.

Your voice matters. Your vote counts.

RSVP TODAY!

Banking With A Purpose

Much more than a catchphrase, our tagline is our passion, our reason why we do what we do. This is the impact of your membership with AGCU. Learn More About Banking with a Purpose More articles Like us on Facebook

How to Avoid Rental Scams

“`html

Avoid Rental Property Scams

Don’t Let Your Search for a Home Become a Costly Mistake

Searching for a rental property can be exciting, but it’s also one of the most common ways scammers target unsuspecting renters. Fake listings, stolen photos, and fraudulent landlords can leave victims without a place to live—and without the money they paid for deposits or application fees.

By learning the warning signs, you can protect your finances and avoid becoming the next victim of a rental scam.

Avoid Rental Property Scams

How Rental Scams Work

Scammers often copy legitimate rental listings, complete with attractive photos and descriptions, then repost them with their own contact information. Others invent properties that don’t exist or advertise homes that aren’t actually available for rent. Their goal is simple: convince you to send money before you discover the truth.


Common Warning Signs

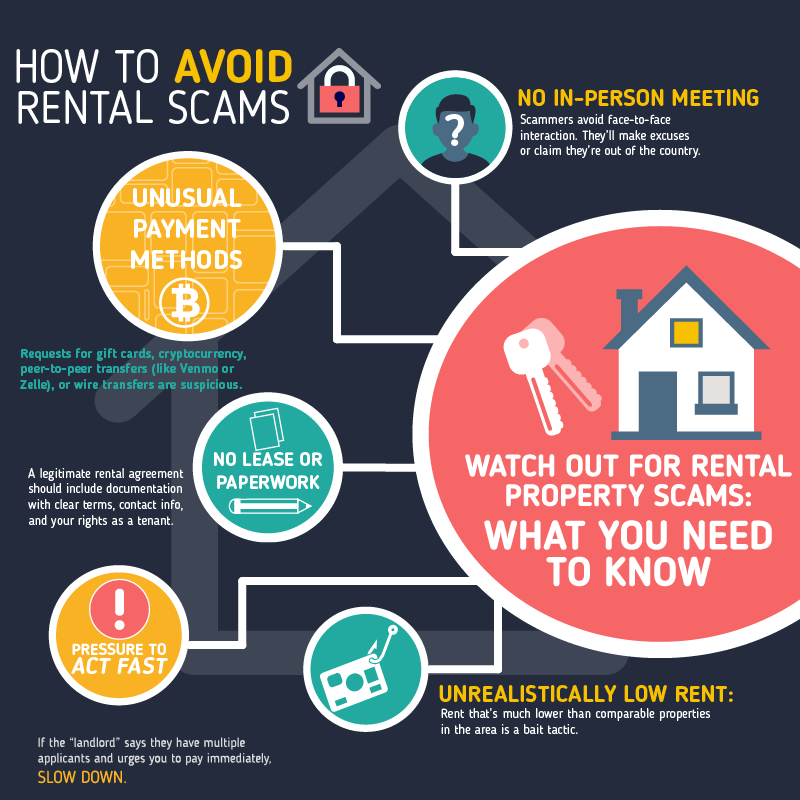
🏠 The Rent Is Too Good to Be True

If a property is significantly less expensive than similar rentals in the area, be cautious. Unrealistically low prices are designed to attract quick responses.

🚫 You Can’t Tour the Property

Scammers often claim they’re out of town, overseas, or unavailable to show the property and ask you to rent it sight unseen.

⏰ They Pressure You to Act Fast

Urgency is a favorite scam tactic. If you’re told someone else is about to rent the property unless you pay immediately, take a step back.

💳 They Want Money Up Front

Be wary of requests to pay deposits, application fees, or the first month’s rent before you’ve verified the property and landlord.

Remember: If someone won’t let you see the property before asking for money, walk away. Legitimate landlords typically allow prospective tenants to view the property before requesting deposits.

How to Protect Yourself

✔ Verify the Listing

  • Search the property address online.
  • Look for duplicate listings with different prices or contact information.
  • Confirm the property is actually available for rent.

✔ Meet the Landlord or Property Manager

Whenever possible, meet in person and tour the property before making any financial commitment.

✔ Research the Owner

Search for the property owner or management company online and verify their contact information independently.

✔ Pay Securely

Avoid wire transfers, gift cards, cryptocurrency, or peer-to-peer payment apps when dealing with someone you haven’t verified.


Never Share Personal Information Too Soon

Some scammers aren’t after your money—they’re after your identity.

Avoid providing your:

  • Social Security number
  • Driver’s license
  • Bank account information
  • Pay stubs
  • Credit report

Only provide sensitive information after you’ve confirmed the property and the landlord are legitimate.


If You Think You’ve Been Scammed

  1. Stop communicating with the suspected scammer.
  2. Do not send additional money.
  3. Contact your financial institution immediately if you’ve shared payment information.
  4. Monitor your accounts for unauthorized activity.
  5. Report the scam to local law enforcement and the Federal Trade Commission.

Rental Scam Prevention Checklist

Before you send money, ask yourself:

  • ☐ Have I toured the property?
  • ☐ Have I verified the landlord or property manager?
  • ☐ Does the rental price match the local market?
  • ☐ Have I researched the property address?
  • ☐ Am I paying through a secure method?
  • ☐ Am I being pressured to act immediately?

Protect Your Money

Rental scams can happen to anyone, but taking a few extra minutes to verify a listing can save you thousands of dollars and countless headaches.

If something doesn’t feel right, trust your instincts. Slow down, ask questions, and verify before you pay.

For more fraud prevention tips, explore AGCU’s Financial Education Center and Scam Prevention resources.

“`

What is a HELOC?

What’s the Difference Between a HELOC and a Home Equity Loan?

Which One Is Right for You?

If you’ve built equity in your home, you may be able to use it to finance home improvements, consolidate debt, cover education expenses, or pay for other major purchases.

Two of the most common ways to borrow against your home’s equity are a Home Equity Line of Credit (HELOC) and a Home Equity Loan.

Although they sound similar, they work differently. Understanding the differences can help you choose the option that best fits your financial goals.

HELOC vs. Home Equity Loan

What Is Home Equity?

Home equity is the difference between your home’s current value and the amount you still owe on your mortgage.

As your home increases in value and you pay down your mortgage, your equity grows. Many homeowners can use a portion of that equity to help finance important life goals.

Example

Home Value: $350,000

Mortgage Balance: $250,000

Available Equity: $100,000


What Is a HELOC?

A Home Equity Line of Credit (HELOC) is a revolving line of credit secured by your home.

Think of it like a credit card. You’re approved for a maximum credit limit and borrow only what you need, when you need it. As you repay what you’ve borrowed, those funds become available again during the draw period.

A HELOC May Be Best For:

  • Home renovations completed over time
  • Multi-phase remodeling projects
  • Ongoing education expenses
  • Emergency expenses
  • Unexpected repairs
  • Situations where you don’t know exactly how much you’ll need

What Is a Home Equity Loan?

A Home Equity Loan provides all of your funds in one lump sum.

Rather than borrowing as needed, you receive the entire loan amount upfront and repay it through fixed monthly payments over a set period of time.

Many Home Equity Loans offer fixed interest rates, making payments more predictable.

A Home Equity Loan May Be Best For:

  • Debt consolidation
  • A new roof or HVAC system
  • Large medical expenses
  • One-time home improvement projects
  • Major purchases with a known cost

HELOC vs. Home Equity Loan

Feature HELOC Home Equity Loan
Funds Received Borrow as needed One lump sum
Payments Based on amount borrowed Fixed monthly payment
Interest Rate Often variable Often fixed
Best For Projects with changing costs Known expenses
Flexibility High Moderate

Which Option Is Right for You?

Choose a HELOC If…

  • You aren’t sure exactly how much you’ll need.
  • Your project will happen over several months.
  • You want flexibility.
  • You only want to borrow what you actually use.
  • You may need additional funds later.

Choose a Home Equity Loan If…

  • You know exactly how much money you need.
  • You prefer predictable monthly payments.
  • You’re paying for one large expense.
  • You like the stability of a fixed interest rate.
  • You want the entire amount immediately.

Benefits of Both

Whether you choose a HELOC or a Home Equity Loan, both can offer advantages over unsecured borrowing.

  • Competitive interest rates
  • Access to larger borrowing amounts
  • Flexible financing options
  • The ability to put your home’s equity to work

Things to Consider Before Borrowing

  • Your home serves as collateral.
  • Many HELOCs have variable interest rates.
  • Borrow only what you can comfortably repay.
  • Have a clear plan for how you’ll use the funds.
  • Consider your long-term financial goals before borrowing.

Frequently Asked Questions

Which has lower monthly payments?

That depends on the amount borrowed, repayment term, and interest rate. A Home Equity Loan generally offers fixed monthly payments, while HELOC payments may change over time.

Can I use either for home improvements?

Absolutely. Both are popular financing options for renovations and repairs.

Can I consolidate debt with either option?

Yes. Many homeowners use both products to consolidate higher-interest debt, though it’s important to understand the risks before using your home as collateral.

Can I borrow my full equity?

Not usually. Lenders typically allow borrowing up to a percentage of your available home equity, subject to credit approval and underwriting guidelines.


Let AGCU Help You Choose

Whether you’re remodeling your home, consolidating debt, or preparing for a major expense, AGCU can help you determine which financing option best fits your needs.

Our mortgage specialists are happy to answer your questions and explain your options—without pressure.

Visit agcuhomeloans.org to learn more or get started today.

Final Thought

A HELOC and a Home Equity Loan both allow you to borrow against the value you’ve built in your home—but they’re designed for different situations.

If you need ongoing flexibility, a HELOC may be the better choice. If you know exactly how much you need and prefer fixed monthly payments, a Home Equity Loan may be a better fit. The best option is the one that aligns with your financial goals.

Equal Housing Lender. Loan approval subject to credit approval, available equity, underwriting requirements, and program guidelines. Your home secures the loan or line of credit.

“`

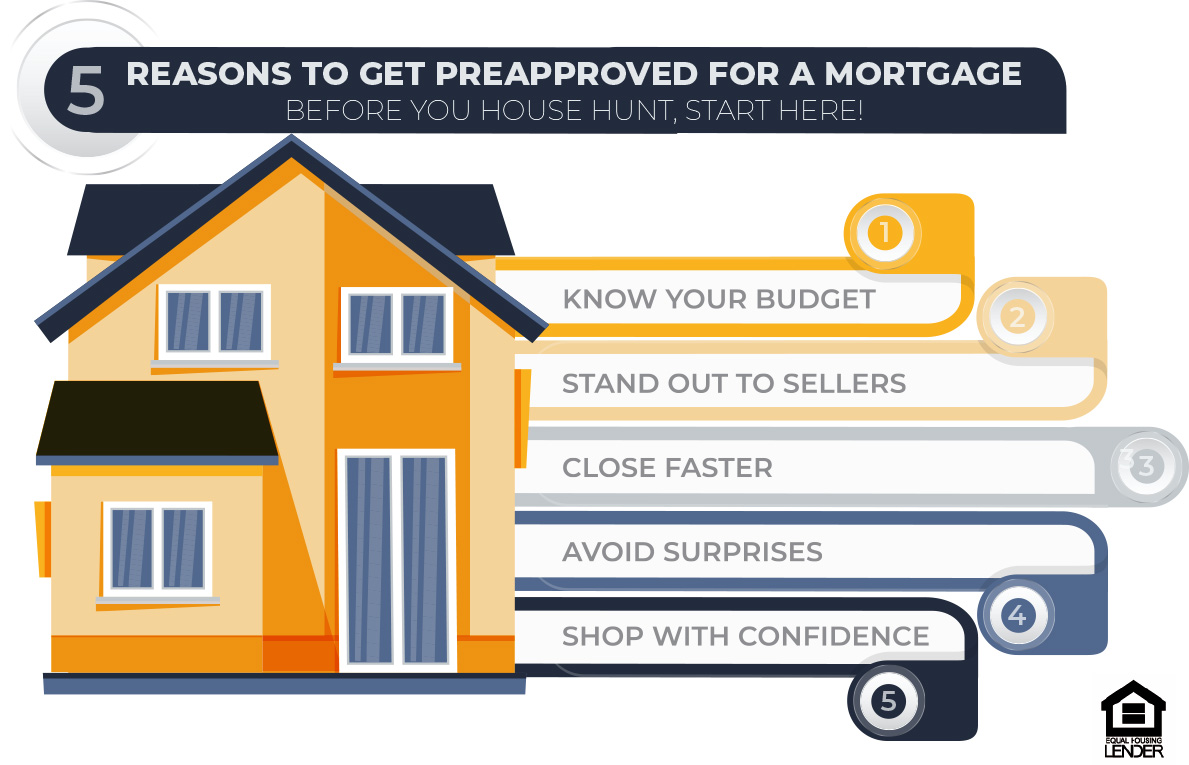
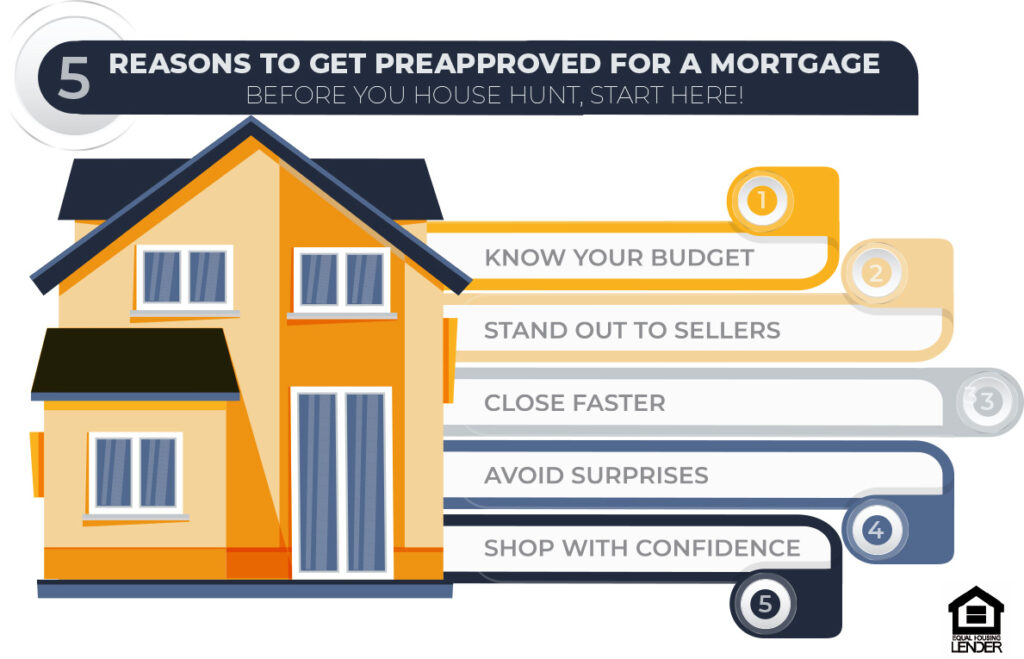
5 Reasons to Get Preapproved for a Mortgage

5 Reasons to Get Preapproved for a Mortgage

A mortgage preapproval can help you shop with confidence and move quickly when you find the right home.

Before you start touring homes, it helps to know how much you may be able to borrow and what monthly payment could fit your budget.

A mortgage preapproval gives you a clearer picture of your buying power and can make the homebuying process smoother from the very beginning.

5 Reasons to Get Preapproved for a Mortgage

What Is Mortgage Preapproval?

A mortgage preapproval is a lender’s conditional review of your finances to estimate how much you may be qualified to borrow. It typically includes a review of your income, credit, debts, and assets.

While preapproval is not a final loan approval, it is an important early step that can help you understand your options before making an offer on a home.

Quick Tip

Getting preapproved before house hunting can save time, reduce stress, and help you focus on homes that fit your budget.

1. Know Your Budget Before You Shop

It is easy to fall in love with a home before knowing whether it fits your finances. Preapproval helps you understand your estimated price range so you can shop more realistically.

Knowing your budget early can also help you compare monthly payments, down payment options, taxes, insurance, and other homeownership costs.

2. Strengthen Your Offer

In a competitive housing market, sellers often want to know that buyers are serious and financially prepared.

A preapproval letter can help show that a lender has reviewed your financial information and that you are ready to move forward if your offer is accepted.

3. Spot Potential Issues Early

The preapproval process may uncover items that need attention, such as credit report errors, documentation needs, or debt-to-income concerns.

Finding these issues before you make an offer gives you more time to address them and helps prevent last-minute delays.

4. Move Faster When You Find the Right Home

Once you find a home you love, things can move quickly. Having preapproval in place may help speed up the offer and loan process.

Instead of starting from scratch, you have already completed part of the financial review, which can help keep the process moving.

5. Shop With More Confidence

Buying a home is a major decision. Preapproval can give you greater confidence as you compare homes, ask questions, and make decisions.

It also helps your real estate agent better understand your goals and guide you toward homes that match your financial picture.

What You May Need for Preapproval

Requirements can vary, but you may be asked to provide:

  • Recent pay stubs or proof of income
  • W-2s or tax documents
  • Bank statements
  • Information about current debts
  • Photo identification
  • Permission to review your credit

Ready to Get Started?

Whether you are buying your first home or preparing for your next move, AGCU’s mortgage team can help you understand your options and take the next step with confidence.

Start your mortgage journey at agcuhomeloans.org.

Final Thought

Preapproval is not just paperwork. It is a helpful tool that can make your home search more focused, more confident, and less stressful.

Before you start shopping, take time to understand your buying power and prepare for the journey ahead.

Equal Housing Lender. Mortgage approval subject to credit approval, underwriting requirements, and program guidelines.

Frequently Asked Questions About Mortgage Pre-approval

It’s best to get preapproved for a mortgage at least 1–3 months before you start house hunting. This gives you time to understand your budget, correct any issues on your credit report, and position yourself as a serious buyer when making an offer.

Most lenders in Missouri look for a minimum credit score of 620 for conventional loans. However, government-backed loans like FHA may allow lower scores. AGCU works with members to find the right mortgage option based on their unique financial situation.

A mortgage preapproval typically involves a hard inquiry on your credit report, which may cause a small, temporary dip in your credit score. However, this impact is usually minimal and well worth the benefits of being preapproved when house hunting.

You could lose your earnest money deposit if you’re denied a mortgage; especially if your purchase contract doesn’t include a financing contingency, which protects you in case your loan falls through. Without this safeguard, a denied loan could mean walking away from a home and your deposit.

That’s why getting preapproved before making an offer is so important. A mortgage preapproval gives you a clearer picture of what you can afford and shows sellers you’re a serious, qualified buyer. It also reduces the risk of loan denial after your offer is accepted. At AGCU, our preapproval process helps set you up for a smoother, more secure homebuying experience from day one.

AGCU Names Peter Shiner as New President & CEO

Springfield, Mo – April 7, 2025– The Assemblies of God Credit Union (AGCU) is pleased to announce the appointment of Peter Shiner as its new President and Chief Executive Officer. With over 15 years of leadership experience in federally insured credit unions and community banks, Shiner brings a strong background in strategic financial management, regulatory compliance, and capital markets expertise.

Shiner joined AGCU as Senior Vice President and Chief Risk Officer. His leadership has played a crucial role in strengthening AGCU’s positioning for long-term growth.

“I am honored to serve as AGCU’s next President and CEO,” said Shiner. “and I look forward to building a high-performing team that understands the power of relationships and values our members’ trust. Together, we will continue to expand our services, embrace new opportunities, and remain a faith-driven financial partner for our members.”

Peter and his wife, Whitney, along with their three young children, are excited to make Springfield their home. They look forward to becoming part of the community and embracing AGCU’s mission of serving members with integrity and care.

Prior to AGCU, Shiner held leadership positions at Performance Trust Capital Partners, First Entertainment Credit Union, and Academy Securities, where he advised executive teams and boards on risk management, investment strategies, and institutional growth. He has overseen multi-billion-dollar loan and fixed-income portfolios, executed over $6.5 billion in asset allocation strategies, and played a pivotal role in enhancing financial institutions’ balance sheet flexibility and growth.

“We are excited to welcome Peter Shiner as our new President and CEO,” said Bill Perkin, treasurer of the AGCU board of directors. “His strategic vision, deep financial expertise, and commitment to faith-based financial services make him the ideal leader to guide AGCU into the future. We look forward to his leadership as we continue to grow and serve our members with excellence.”

Shiner holds an MBA from Azusa Pacific University and a BA from Wheaton College. A former NCAA baseball athlete and Eagle Scout, he brings a disciplined, results-driven approach to leadership.

As CEO, Shiner will focus on expanding AGCU’s financial services, strengthening member engagement, and ensuring the credit union remains a trusted partner for churches, ministries, and individuals seeking financial solutions aligned with their values. 

For more information, visit www.agcu.org.

What is Banking With a Purpose?
Banking with a Purpose at AGCU goes beyond traditional financial services. It is about connecting your faith, family, and finances. Our mission is to improve the lives of our members by providing financial solutions for individuals, ministries, and businesses related to the Assemblies of God fellowship.

Our commitment includes giving back to the community. Each year, we tithe 10% of our annual earnings to support various initiatives, ranging from church planting, ministries and humanitarian projects to educational advancements and scholarships. Join us at AGCU and see how Banking with a Purpose can make a difference in your life and community.

Honoring Bruce Webb’s Leadership & Legacy at AGCU

After a decade of dedicated leadership, Bruce Webb is retiring as President & CEO of Assemblies of God Credit Union (AGCU) in Springfield, MO, Friday, April 4, 2025. His impact on our credit union and its mission has been profound.

Bruce joined AGCU in 2015, bringing 30 years of banking experience from Michigan and Minnesota, along with 40 years of involvement in the Assemblies of God fellowship. Upon arriving, he redefined AGCU’s vision: “To be the most relevant faith-based credit union in the world.” Over the past ten years, AGCU has lived out this vision, serving more than 18,000 members—including over 2,300 missionaries in 190 countries—while remaining deeply connected to the Assemblies of God fellowship.

“Bruce Webb’s leadership over the past decade has transformed AGCU, driving growth, innovation, and a stronger commitment to faith-based financial stewardship,” said Bill Perkin, treasurer, AGCU board of directors. “His vision and dedication have modernized our services and expanded our impact, leaving a lasting legacy. We are deeply grateful for his leadership and the foundation he has built for AGCU’s future.”

Under Bruce’s leadership, AGCU has reached remarkable milestones:

Growth & Expansion

  • Tripled in size, becoming the largest credit union in the greater Springfield, MO area
  • Ranked among the Top Five largest faith-based credit unions in the country
  • Named Missouri’s fastest-growing credit union in 2022 and ranked in the Top 1% of fastest-growing credit unions nationwide
  • Expanded membership eligibility from five states to all 50 states for Assemblies of God church adherents
  • Achieved an average 6% annual membership growth

Financial Strength

  • Recognized as one of the Top 100 Best Performing U.S. Credit Unions of 2022 by S&P Global Market Intelligence
  • Increased total deposits by 155% and loan balances by 245%
  • Grew revenue by 223%, capital by 125%, and net income by 373%

Community Impact & Mission Advancement

  • Donated over $2.5 million to education, ministry, and humanitarian causes
  • Became the second-largest PPP loan originator among Missouri credit unions (2020-2021)
  • Mortgage lending team ranked among the Top 10 in Springfield, MO
  • Expanded commercial, business, and church lending from $10 million to over $110 million

Innovation & Modernization

  • Introduced Video Banking, allowing members to connect via mobile, computer, or in-branch
  • Completed a full rebrand, including a new logo, bold new colors, and a refreshed tagline to reflect our mission and to strengthen our brand
  • Renovated all AGCU buildings, enhancing both exterior and interior spaces
  • Completed a banking software upgrade that added convenience and security for mobile and online users

Bruce’s vision and leadership have left an enduring legacy, ensuring a strong foundation for AGCU’s future. While he and his wife, Kimberley, will remain in Springfield, they look forward to spending more time with family—especially their four grandsons in southern Michigan.

Please join us in thanking Bruce for his years of service and leadership. We are deeply grateful for his impact on AGCU and the communities we serve.

With gratitude,
The AGCU Family

Budgeting Basics: Take Control of Your Money (and Your Future)

Budgeting doesn’t have to be overwhelming. Whether you’re just starting college, entering the workforce, or navigating life on your own, learning how to manage your money is key to financial success. In this guide, we’ll walk you through budgeting basics, practical money tips for young adults, and how AGCU’s financial tools—like high-yield checking, savings accounts, and digital banking—can help you stay on track.

7 Tips For Avoiding Common Money Mistakes – And Fixing Them With AGCU

Managing your money doesn’t come with an instruction manual — and even the most financially responsible people make a few missteps. The good news? Most common money mistakes are easy to fix with a little awareness, a solid plan, and the right financial tools.

Here are some of the most common pitfalls — and how to avoid them using AGCU’s services to build a stronger financial future

Avoiding Common Money Mistakes

1. Ignoring Your Financial Situation

The Problem:
It’s easy to coast through daily life without knowing how much money is in your account, how much debt you owe, or even what your credit score is. But ignoring your finances can lead to overdrafts, missed payments, and a lack of savings when you need it most.

The Fix:
Take time to regularly check your balances, track spending, and monitor your progress toward financial goals. Budgeting apps, online banking tools, and simple spreadsheets can help you stay organized.

AGCU Solution:
Use Online & Mobile Banking to track your accounts anytime, anywhere. And make your money work harder with a FREE Loyalty Plus High Yield Checking Account — you’ll earn competitive interest just by managing your money well.

2. Not Having Clear Financial Goals

The Problem:
Without goals, it’s easy to spend impulsively and wonder where your money went. A lack of direction can lead to missed opportunities and little progress toward long-term dreams.

The Fix:
Set short-term and long-term goals — like building an emergency fund, saving for a home, or preparing for retirement. Goals help you focus your spending and stay motivated.

AGCU Solution:
Open a Savings Account to get started, or Money Market Account for higher returns and easy access to your funds. Planning for retirement? Consider an IRA to help your savings grow tax-advantaged over time.

3. Failing to Communicate About Money

The Problem:
Many couples or families avoid talking about money to prevent conflict — but this often leads to confusion, mismatched priorities, and financial stress.

The Fix:
Set time aside for open, honest money conversations. Align on spending habits, savings goals, and shared responsibilities to build trust and teamwork.

AGCU Solution:
Use Shared Accounts to make managing household finances easier, and explore tools like online bill pay and alerts to stay in sync and avoid surprises. All of these are included for FREE with AGCU Online and Mobile Banking.

4. Not Planning for Medical Expenses

The Problem:
Medical costs can pop up unexpectedly, and without a plan in place, they can derail your budget or lead to debt.

The Fix:
Start saving ahead for future health-related needs. A dedicated account helps ensure you’re financially prepared for out-of-pocket expenses.

AGCU Solution:
Open a Health Savings Account (HSA) to save pre-tax dollars for qualified medical expenses. Funds roll over year to year, and you stay in control of how and when they’re used.

5. Letting Savings Sit Idle

The Problem:
Many people leave money in basic accounts that don’t earn much interest — which means you’re missing out on potential growth.

The Fix:
Reevaluate where you’re storing your savings. Even small improvements in your interest rate can add up over time.

AGCU Solution:
Upgrade your savings strategy with a FREE Loyalty Plus High Yield Checking Account or Money Market Account. These options offer higher returns while keeping your money accessible. Or, if you won’t need immediate access to funds, consider a CD for more competitive rates.

6. Not Building an Emergency Fund

The Problem:
Life is unpredictable — and without an emergency fund, even a small surprise expense can throw off your finances or push you into debt.

The Fix:
Aim to save at least a few months’ worth of expenses. Set up automatic transfers to make saving consistent and painless.

AGCU Solution:
Start with an AGCU Savings Account, and set up recurring transfers from your checking account to grow your cushion over time.

7. Relying Too Much on Credit

The Problem:
It’s easy to fall into the habit of swiping now and worrying later. High-interest credit card debt can build quickly and make it harder to save.

The Fix:
Use credit responsibly, and focus on paying down high-interest balances first. Be mindful of your credit utilization to protect your credit score.

AGCU Solution:
AGCU offers low-rate credit cards and personal loans to help you manage or consolidate debt. Use these tools to regain control and reduce interest costs.

Start Smart, Stay Strong

Avoiding these common money mistakes can help you build financial stability and confidence. Whether you’re just starting your savings journey or optimizing your current strategy, AGCU offers tools to help you succeed every step of the way — from checking and savings accounts, to IRAs, Health Savings Accounts, credit cards, and more.

💡 Ready to take control of your financial future? Learn more about Banking with a Purpose and open an account today.

Banking With A Purpose

Much more than a catchphrase, our tagline is our passion, our reason why we do what we do. This is the impact of your membership with AGCU. Learn More About Banking with a Purpose

Like us on Facebook!

Is My Tax Refund Too Large?

Tax season is here, and if you’re expecting a big refund, you might be feeling like you hit the jackpot! But before you start planning how to spend that extra cash, it’s important to ask: Is my tax refund too big? Let’s break down what it means when you receive a large refund, why it may not be in your best interest, and what steps you can take to better manage your money throughout the year.

Unlocking the Power of Compound Interest: How to Make Your Money Work for You

Unlocking the Power of Compound Interest: How to Make Your Money Work for You

The Earlier You Start, the Greater the Reward

Have you ever heard someone say, “Let your money work for you”? They’re talking about one of the most powerful concepts in personal finance: compound interest.

Compound interest allows your savings to earn interest—not only on the money you deposit, but also on the interest you’ve already earned. Over time, this “interest on interest” can dramatically increase the value of your savings, especially when you start early and save consistently. :contentReference[oaicite:0]{index=0}

Compound Interest

What Is Compound Interest?

Unlike simple interest, which only earns interest on your original deposit, compound interest earns interest on both your principal and your accumulated interest.

::contentReference[oaicite:1]{index=1}

Think of it like a snowball rolling down a hill. As it rolls, it gathers more snow, becoming larger and larger. Compound interest works the same way—your money grows, then that growth begins earning even more growth. :contentReference[oaicite:2]{index=2}


A Simple Example

Suppose you deposit $1,000 into an account earning 5% annually.

Year Account Balance
1 $1,050.00
2 $1,102.50
5 $1,276.28
10 $1,628.89

Notice that every year your interest earns additional interest. The longer you leave your money invested, the faster it grows. :contentReference[oaicite:3]{index=3}


Time Is Your Greatest Asset

When it comes to compound interest, time matters more than almost anything else.

Start Early

Even small deposits made in your 20s can grow substantially over several decades.

Stay Consistent

Adding money regularly allows your balance—and your future earnings—to continue growing.

Be Patient

Compound growth starts slowly but accelerates dramatically over time.


Ways to Take Advantage of Compound Interest

  • Open a savings account and contribute regularly.
  • Consider a Money Market Account for higher balances.
  • Invest in Certificates of Deposit (CDs) when appropriate.
  • Contribute to retirement accounts consistently.
  • Reinvest your earnings whenever possible.

What Can Slow Compound Growth?

  • Waiting too long to begin saving.
  • Frequently withdrawing money.
  • Only making occasional deposits.
  • Paying high-interest debt instead of building savings.

Compound Interest Can Work Against You, Too

Compound interest isn’t only beneficial—it also explains why credit card debt can become expensive so quickly.

When you carry a balance month after month, you’re paying interest on previous interest charges. That’s why paying your credit card balance in full whenever possible can save you hundreds or even thousands of dollars over time. :contentReference[oaicite:4]{index=4}


💡 Money-Saving Tip

You don’t need thousands of dollars to benefit from compound interest. Starting with a small amount and saving consistently is often more important than waiting until you can save more.


Frequently Asked Questions

How often is interest compounded?

Depending on the account, interest may be compounded daily, monthly, quarterly, or annually. More frequent compounding generally results in faster growth. :contentReference[oaicite:5]{index=5}

What accounts earn compound interest?

Savings accounts, Money Market Accounts, Certificates of Deposit, many retirement accounts, and numerous investment accounts all benefit from compound growth. :contentReference[oaicite:6]{index=6}

Is compound interest guaranteed?

For deposit accounts like savings, Money Market Accounts, and CDs, interest is earned according to the account’s disclosed rate. Investment returns, however, are not guaranteed and can fluctuate.


Start Building Your Future Today

One of the best times to begin saving was years ago. The second-best time is today.

Whether you’re saving for an emergency fund, a home, retirement, or your children’s future, giving compound interest more time to work can make a meaningful difference.

At AGCU, we’re here to help you choose the savings options that fit your goals and put the power of compound interest to work for you.