How to transfer money with Zelle®

“`html

How to Transfer Money with Zelle®

Send Money to Friends and Family in Minutes

Zelle® makes it easy to send and receive money directly from your AGCU account using Online Banking or Mobile Banking.

Whether you’re paying a friend back for lunch, splitting expenses, or sending money to a family member, Zelle® offers a fast and convenient way to move money between eligible U.S. bank accounts. Money is typically available within minutes when both parties are enrolled.¹

Send Money with Zelle

What Is Zelle®?

Zelle® is a digital payment service built into AGCU Online Banking and Mobile Banking. Instead of using cash, checks, or third-party payment apps, you can send money directly from your AGCU account to someone else’s eligible U.S. bank account using only their email address or mobile phone number.

Important: Only send money to people you know and trust. Zelle® payments are designed for friends, family, and trusted contacts and generally cannot be canceled once the recipient is enrolled.

How to Enroll in Zelle®

Step 1

Log into AGCU Mobile Banking or Online Banking.

Step 2

Select Transfer and Pay and then Send Money with Zelle®.

Step 3

Enroll your email address or U.S. mobile phone number.

Step 4

Start sending and receiving money.
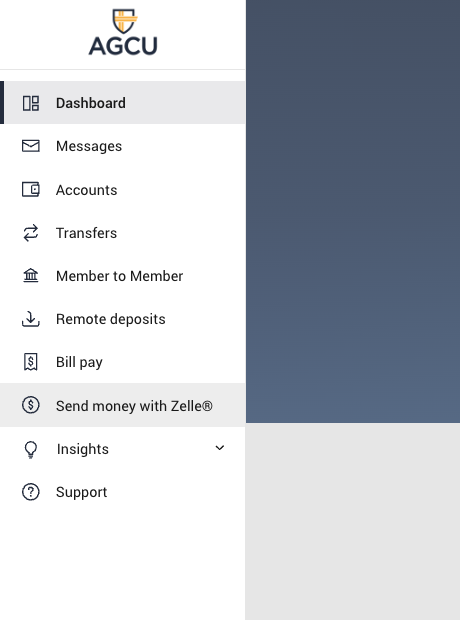
Enroll in Zelle

How to Send Money

  1. Select Send Money with Zelle®.
  2. Choose a recipient from your contacts or enter their email address or U.S. mobile number.
  3. Enter the amount.
  4. Add an optional memo.
  5. Review and confirm the payment.

If your recipient is already enrolled with Zelle®, the money is typically available within minutes.¹


How to Receive Money

Receiving money is simple:

  • Share your enrolled email address or U.S. mobile number.
  • Ask the sender to send money using Zelle®.
  • The funds are deposited directly into your enrolled AGCU account.

If you have already enrolled, no additional action is required to receive payments.


How to Request Money

Need to collect money from a friend, roommate, or family member?

  1. Select Request inside Zelle®.
  2. Choose your recipient.
  3. Enter the amount requested.
  4. Add an optional note.
  5. Send the request.

Your recipient will receive a notification and can send payment directly through their participating financial institution.


Using Zelle® QR Codes

Zelle® QR Codes allow you to send money without typing an email address or phone number.

  • Open Zelle® within Online Banking or Mobile Banking.
  • Select the QR Code icon.
  • Scan the recipient’s QR Code.
  • Verify the recipient.
  • Enter the amount and send.

QR Codes help reduce the risk of sending money to the wrong person.


Zelle® Limits at AGCU

Limit Type Amount
Per Transaction $500
Daily Limit $500
Weekly Limit $600
Monthly Limit $2,400

Transaction limits may change over time. Contact Member Care for current limits.


Frequently Asked Questions

Are there fees to use Zelle®?

Most consumers can send and receive money with Zelle® without paying a fee.²

Can I cancel a payment?

You can only cancel a payment if the recipient has not yet enrolled with Zelle®. Once an enrolled recipient receives the funds, the payment generally cannot be reversed.

Can I use Zelle® internationally?

No. Both the sender and recipient must have eligible U.S. bank accounts.

What does the purple “Z” mean?

The purple “Z” indicates a contact who is already enrolled with Zelle®.

What if my phone number is already enrolled elsewhere?

If your email address or mobile number is already associated with another financial institution’s Zelle® profile, contact Member Care for assistance moving it to AGCU.


Send Money with Confidence

Zelle® offers a convenient way to send money directly from your AGCU account without sharing account numbers.

Whether you’re paying a friend back, splitting expenses, or sending money to family, Zelle® helps you move money quickly and securely.

¹ Transactions between enrolled users typically occur within minutes.
² Check with AGCU for any applicable account or service fees.

“`

2025 Scholarship Recipients

Congratulations to the recipients of our 2025 AGCU Scholarships!

Winners were announced Thursday, June 19 at the Annual Business Meeting held at Central Assembly. Every year we award scholarships to a number of Youth Account Members who are graduating from high school and plan to attend an accredited college or university in the fall of their graduation year. It’s just our way of thanking our youth account members who have chosen AGCU as their banking institution. If you would like to learn if you or a loved one qualify for an AGCU Scholarship, contact your local branch!

Javan Brown

Javan Brown

$3000 Scholarship
Javan is graduating from Trivium Preparatory Academy in Goodyear, Arizona, and plans to attend Barrett, The Honors College at Arizona State University as a Finance major. Javan volunteers at Mercy House Community Center and regularly helps organize food drives, back-to-school supply distribution and Christmas toy drives. He serves on the tech team and student ministries team at his church, as well as playing keyboard for the Youth Worship Team.

Jonathan Buck

Jonathan Buck

$3000 Scholarship
Jonathan is graduating from Allendale Academy in Clearwater, FL, and plans to attend Embry-Riddle Aeronautical University in Daytona Beach, FL as an Engineering Technology major.Since studying via distance learning overseas as a missionary, he has been unable to participate in school activities like most Americans. However, he was able to take part in several sports clubs like swimming, rollerblading, Krav Maga and archery. He has also taken piano lessons since 2012. Jonathan volunteers at Gospel Vision, an international ministry by creating Reels, Shorts and TikToks from weekly services and TV programs to post on social media.

Micah Hufman

Micah Hufman

$3000 Scholarship
Micah is graduating from Hillcrest High School in Springfield, Missouri, and plans to attend Ozark Technical College and study to be an aviation technician. He has been on the Varsity Soccer and Archery Golf teams throughout his high school career, as well as, participated in FFA, 4-H and JROTC while holding placement on the Honor Roll. Micah received the Military Order of the Purple Heart National Leadership Award in 2022 along with multiple other awards and achievements. He volunteers at Grant Beach Sports Association and his church. Micah is on several teams at church, including Media Team, Kids’ Ministry, Prayer Team and Events Team.

Carter McDaniel

Carter McDaniel

$3000 Scholarship
Carter is graduating from McDaniel Academy that he attends from his home in Springfield, MO and plans to attend Evangel University as a business major. He has participated in Classical Christian Academy Speech & Debate for the past 4 years and been part of the Lighthouse Chargers Baseball team. He is a tech volunteer at his church where he is active in the youth group and serves in the kids’ ministry in various roles. Additionally, he volunteers at community events for Convoy of Hope

Grace Whalen

Grace Whalen

$3000 Scholarship
Grace is graduating from New Covenant Academy in Springfield, Missouri, and plans to attend Southwest Baptist University to study nursing. There she has been on the volleyball team and part of the cheerleading squad. She was inducted into the National Honors Society in 2024. She has also served as the Student Council Art Commissioner at New Covenant Academy. She has helped at Nixa Community Center in her spare time as a volleyball coach and referee, as well as assisting teachers with tutoring elementary students in the A+ Program.

Flinton Evans

Flinton Evans

$1,000 Merrell K. Cooper Memorial Scholarship
Flinton is graduating from Logan-Rogersville High School in Rogersville, Missouri, and plans to attend Missouri State University as a criminal justice major. He is a member of the high school concert band and marching band. He has also competed on the trapshooting team at the varsity level. He is also Vice President of the Rogersville National Honors Society Chapter. He is involved with his church youth group and volunteers at the Least of These Food Pantry in Ozark, MO.

Robocalls: What You Need to Know (and How to Stop Them)

Robocalls: What You Need to Know

How to recognize suspicious calls, reduce unwanted interruptions, and protect your information.

Robocalls have become a persistent and disruptive part of everyday life. Some are legitimate, such as appointment reminders or school notifications, but many are scams designed to steal personal information or money.

Knowing how robocalls work can help you avoid becoming a victim and protect your financial security.

Robocalls: What You Need to Know

Why Robocalls Can Be Dangerous

Robocalls are dangerous because they often serve as the first step in fraud, identity theft, or financial scams. Scammers may impersonate government agencies, financial institutions, or well-known companies to pressure people into sharing sensitive information. Even answering a robocall can confirm that your number is active, which may lead to more unwanted calls. Pressing a button, speaking to the caller, or following instructions can increase your risk.

Quick Safety Rule

If you do not recognize the number, let it go to voicemail. If the call is legitimate, the caller can leave a message.

How to Spot a Robocall

Robocalls can be sneaky, but there are warning signs that can help you recognize a suspicious call before you engage.
  • Pre-recorded messages that begin as soon as the call connects
  • Caller ID spoofing, where the number looks local or familiar
  • Urgent threats, including legal action or arrest warnings
  • Unsolicited offers that sound too good to be true
  • Requests for Social Security numbers, passwords, or account information
  • Demands for payment by gift card, wire transfer, or cryptocurrency
  • Pressure to act immediately or avoid asking questions
Spotting even one of these red flags is a good reason to hang up and verify the information independently.

How to Avoid Robocall Scams

The best protection is a combination of awareness and prevention. Avoid answering unfamiliar numbers whenever possible. If you do answer, do not provide information, press buttons, or follow instructions from the call.

Do

  • Let unknown calls go to voicemail
  • Verify suspicious claims directly
  • Use call-blocking tools
  • Report scam calls when possible

Do Not

  • Press numbers to “be removed”
  • Share personal information
  • Send money after an unexpected call
  • Trust caller ID alone

How to Reduce Robocalls

Register with the National Do Not Call Registry

Add your phone number to the National Do Not Call Registry at donotcall.gov.

Use Call-Blocking Tools

Many phone carriers and smartphones offer built-in call-blocking or spam-filtering tools. You may also consider reputable call-blocking apps.

Know Useful Phone Codes

  • *67 — Blocks your number so caller ID shows “Private”
  • *61 — Blocks the last call on some landline services
  • *82 — Unblocks caller ID if you previously hid your number
If you are receiving dozens of robocalls daily, changing your number may help, but it is usually a last resort.

What to Do If You Think You’ve Been Scammed

If you believe you have fallen victim to a robocall scam, act quickly but stay calm.
  1. Hang up immediately.
  2. Contact your bank or credit union if you shared financial information.
  3. Check your accounts for unauthorized transactions.
  4. Report the scam to the FTC at ReportFraud.ftc.gov.
  5. Report unwanted robocalls to the FCC at consumercomplaints.fcc.gov.
  6. Warn friends and family so they can stay alert.

Protect Your Identity. Protect Your Finances.

At AGCU, we care about your financial security. If you believe your personal or financial information has been compromised, contact us right away.

We can help you take steps to secure your accounts and protect your information.

Robocall FAQ

Can a robocall hack your phone?

Not directly. However, if you follow instructions from a scammer, download an app, or visit a malicious website, you could expose your device to malware or data theft.

What if I say “yes” during a robocall?

Scammers may record your voice and attempt to misuse it. Avoid answering suspicious calls with personal affirmations or account information.

Why am I suddenly getting so many robocalls?

It could be due to leaked data, caller ID spoofing, or a recycled phone number with a history of scam calls.

Can someone track me with my phone number?

Not easily, but scammers may collect public information connected to your number and use it in social engineering attempts.

Should I answer or ignore robocalls?

Ignore calls from unknown numbers when possible. If the caller is legitimate, they can leave a voicemail.

Should I press a number to stop the calls?

No. Pressing a number can confirm your phone number is active and may lead to more unwanted calls.

Final Thought

Robocalls are more than annoying—they can be dangerous.

Stay cautious, avoid engaging with suspicious calls, and verify unexpected requests through trusted channels before sharing information or sending money.

How to Avoid Rental Scams

“`html

Avoid Rental Property Scams

Don’t Let Your Search for a Home Become a Costly Mistake

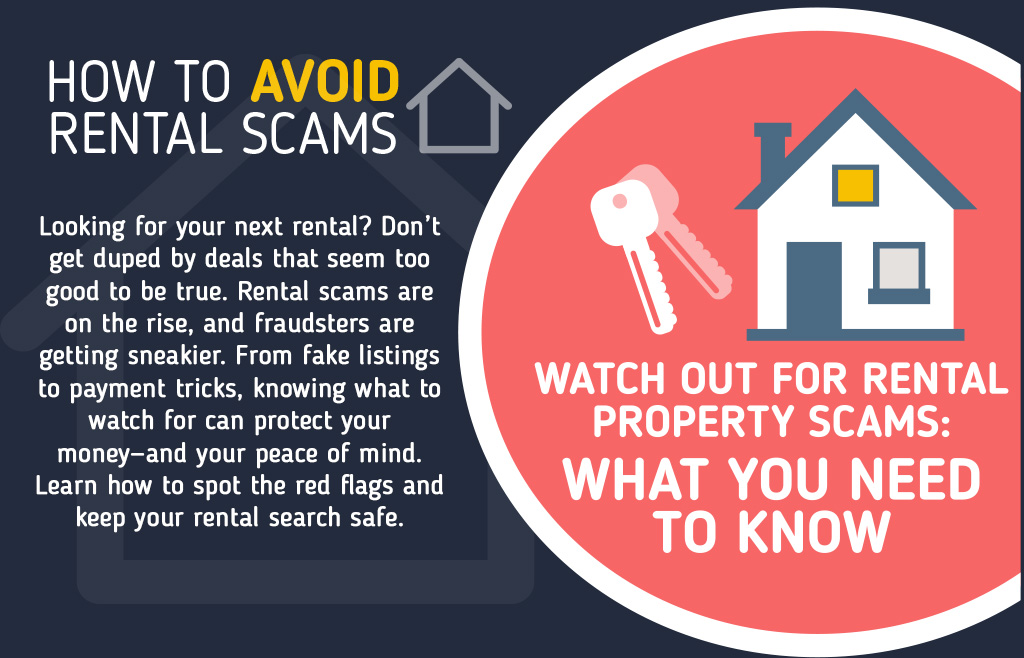
Searching for a rental property can be exciting, but it’s also one of the most common ways scammers target unsuspecting renters. Fake listings, stolen photos, and fraudulent landlords can leave victims without a place to live—and without the money they paid for deposits or application fees.

By learning the warning signs, you can protect your finances and avoid becoming the next victim of a rental scam.

Avoid Rental Property Scams

How Rental Scams Work

Scammers often copy legitimate rental listings, complete with attractive photos and descriptions, then repost them with their own contact information. Others invent properties that don’t exist or advertise homes that aren’t actually available for rent. Their goal is simple: convince you to send money before you discover the truth.


Common Warning Signs

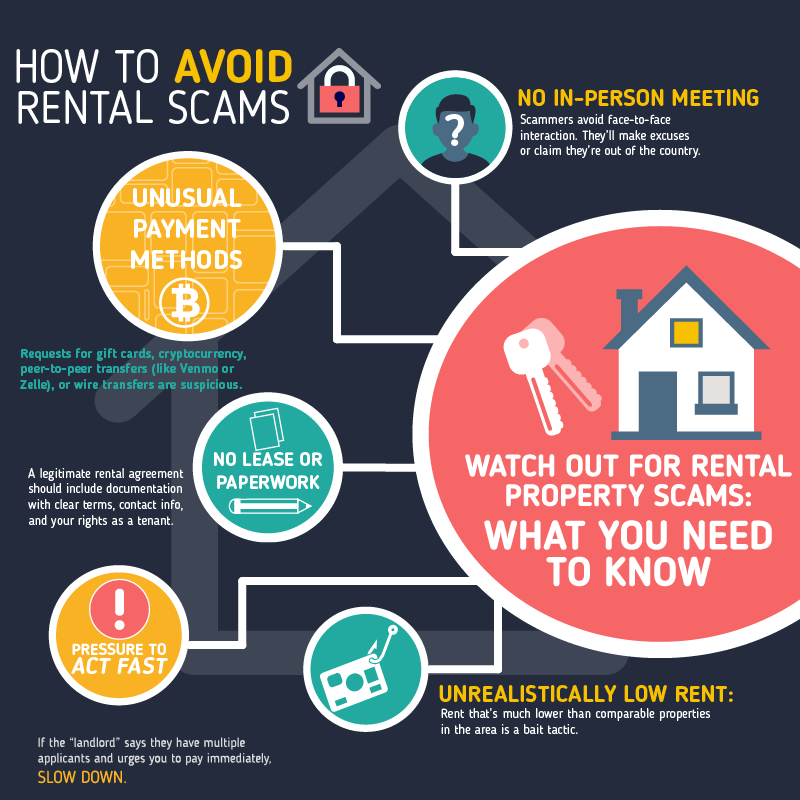
🏠 The Rent Is Too Good to Be True

If a property is significantly less expensive than similar rentals in the area, be cautious. Unrealistically low prices are designed to attract quick responses.

🚫 You Can’t Tour the Property

Scammers often claim they’re out of town, overseas, or unavailable to show the property and ask you to rent it sight unseen.

⏰ They Pressure You to Act Fast

Urgency is a favorite scam tactic. If you’re told someone else is about to rent the property unless you pay immediately, take a step back.

💳 They Want Money Up Front

Be wary of requests to pay deposits, application fees, or the first month’s rent before you’ve verified the property and landlord.

Remember: If someone won’t let you see the property before asking for money, walk away. Legitimate landlords typically allow prospective tenants to view the property before requesting deposits.

How to Protect Yourself

✔ Verify the Listing

  • Search the property address online.
  • Look for duplicate listings with different prices or contact information.
  • Confirm the property is actually available for rent.

✔ Meet the Landlord or Property Manager

Whenever possible, meet in person and tour the property before making any financial commitment.

✔ Research the Owner

Search for the property owner or management company online and verify their contact information independently.

✔ Pay Securely

Avoid wire transfers, gift cards, cryptocurrency, or peer-to-peer payment apps when dealing with someone you haven’t verified.


Never Share Personal Information Too Soon

Some scammers aren’t after your money—they’re after your identity.

Avoid providing your:

  • Social Security number
  • Driver’s license
  • Bank account information
  • Pay stubs
  • Credit report

Only provide sensitive information after you’ve confirmed the property and the landlord are legitimate.


If You Think You’ve Been Scammed

  1. Stop communicating with the suspected scammer.
  2. Do not send additional money.
  3. Contact your financial institution immediately if you’ve shared payment information.
  4. Monitor your accounts for unauthorized activity.
  5. Report the scam to local law enforcement and the Federal Trade Commission.

Rental Scam Prevention Checklist

Before you send money, ask yourself:

  • ☐ Have I toured the property?
  • ☐ Have I verified the landlord or property manager?
  • ☐ Does the rental price match the local market?
  • ☐ Have I researched the property address?
  • ☐ Am I paying through a secure method?
  • ☐ Am I being pressured to act immediately?

Protect Your Money

Rental scams can happen to anyone, but taking a few extra minutes to verify a listing can save you thousands of dollars and countless headaches.

If something doesn’t feel right, trust your instincts. Slow down, ask questions, and verify before you pay.

For more fraud prevention tips, explore AGCU’s Financial Education Center and Scam Prevention resources.

“`

AGCU Names Peter Shiner as New President & CEO

Springfield, Mo – April 7, 2025– The Assemblies of God Credit Union (AGCU) is pleased to announce the appointment of Peter Shiner as its new President and Chief Executive Officer. With over 15 years of leadership experience in federally insured credit unions and community banks, Shiner brings a strong background in strategic financial management, regulatory compliance, and capital markets expertise.

Shiner joined AGCU as Senior Vice President and Chief Risk Officer. His leadership has played a crucial role in strengthening AGCU’s positioning for long-term growth.

“I am honored to serve as AGCU’s next President and CEO,” said Shiner. “and I look forward to building a high-performing team that understands the power of relationships and values our members’ trust. Together, we will continue to expand our services, embrace new opportunities, and remain a faith-driven financial partner for our members.”

Peter and his wife, Whitney, along with their three young children, are excited to make Springfield their home. They look forward to becoming part of the community and embracing AGCU’s mission of serving members with integrity and care.

Prior to AGCU, Shiner held leadership positions at Performance Trust Capital Partners, First Entertainment Credit Union, and Academy Securities, where he advised executive teams and boards on risk management, investment strategies, and institutional growth. He has overseen multi-billion-dollar loan and fixed-income portfolios, executed over $6.5 billion in asset allocation strategies, and played a pivotal role in enhancing financial institutions’ balance sheet flexibility and growth.

“We are excited to welcome Peter Shiner as our new President and CEO,” said Bill Perkin, treasurer of the AGCU board of directors. “His strategic vision, deep financial expertise, and commitment to faith-based financial services make him the ideal leader to guide AGCU into the future. We look forward to his leadership as we continue to grow and serve our members with excellence.”

Shiner holds an MBA from Azusa Pacific University and a BA from Wheaton College. A former NCAA baseball athlete and Eagle Scout, he brings a disciplined, results-driven approach to leadership.

As CEO, Shiner will focus on expanding AGCU’s financial services, strengthening member engagement, and ensuring the credit union remains a trusted partner for churches, ministries, and individuals seeking financial solutions aligned with their values. 

For more information, visit www.agcu.org.

What is Banking With a Purpose?
Banking with a Purpose at AGCU goes beyond traditional financial services. It is about connecting your faith, family, and finances. Our mission is to improve the lives of our members by providing financial solutions for individuals, ministries, and businesses related to the Assemblies of God fellowship.

Our commitment includes giving back to the community. Each year, we tithe 10% of our annual earnings to support various initiatives, ranging from church planting, ministries and humanitarian projects to educational advancements and scholarships. Join us at AGCU and see how Banking with a Purpose can make a difference in your life and community.

Honoring Bruce Webb’s Leadership & Legacy at AGCU

After a decade of dedicated leadership, Bruce Webb is retiring as President & CEO of Assemblies of God Credit Union (AGCU) in Springfield, MO, Friday, April 4, 2025. His impact on our credit union and its mission has been profound.

Bruce joined AGCU in 2015, bringing 30 years of banking experience from Michigan and Minnesota, along with 40 years of involvement in the Assemblies of God fellowship. Upon arriving, he redefined AGCU’s vision: “To be the most relevant faith-based credit union in the world.” Over the past ten years, AGCU has lived out this vision, serving more than 18,000 members—including over 2,300 missionaries in 190 countries—while remaining deeply connected to the Assemblies of God fellowship.

“Bruce Webb’s leadership over the past decade has transformed AGCU, driving growth, innovation, and a stronger commitment to faith-based financial stewardship,” said Bill Perkin, treasurer, AGCU board of directors. “His vision and dedication have modernized our services and expanded our impact, leaving a lasting legacy. We are deeply grateful for his leadership and the foundation he has built for AGCU’s future.”

Under Bruce’s leadership, AGCU has reached remarkable milestones:

Growth & Expansion

  • Tripled in size, becoming the largest credit union in the greater Springfield, MO area
  • Ranked among the Top Five largest faith-based credit unions in the country
  • Named Missouri’s fastest-growing credit union in 2022 and ranked in the Top 1% of fastest-growing credit unions nationwide
  • Expanded membership eligibility from five states to all 50 states for Assemblies of God church adherents
  • Achieved an average 6% annual membership growth

Financial Strength

  • Recognized as one of the Top 100 Best Performing U.S. Credit Unions of 2022 by S&P Global Market Intelligence
  • Increased total deposits by 155% and loan balances by 245%
  • Grew revenue by 223%, capital by 125%, and net income by 373%

Community Impact & Mission Advancement

  • Donated over $2.5 million to education, ministry, and humanitarian causes
  • Became the second-largest PPP loan originator among Missouri credit unions (2020-2021)
  • Mortgage lending team ranked among the Top 10 in Springfield, MO
  • Expanded commercial, business, and church lending from $10 million to over $110 million

Innovation & Modernization

  • Introduced Video Banking, allowing members to connect via mobile, computer, or in-branch
  • Completed a full rebrand, including a new logo, bold new colors, and a refreshed tagline to reflect our mission and to strengthen our brand
  • Renovated all AGCU buildings, enhancing both exterior and interior spaces
  • Completed a banking software upgrade that added convenience and security for mobile and online users

Bruce’s vision and leadership have left an enduring legacy, ensuring a strong foundation for AGCU’s future. While he and his wife, Kimberley, will remain in Springfield, they look forward to spending more time with family—especially their four grandsons in southern Michigan.

Please join us in thanking Bruce for his years of service and leadership. We are deeply grateful for his impact on AGCU and the communities we serve.

With gratitude,
The AGCU Family

7 Tips For Avoiding Common Money Mistakes – And Fixing Them With AGCU

Managing your money doesn’t come with an instruction manual — and even the most financially responsible people make a few missteps. The good news? Most common money mistakes are easy to fix with a little awareness, a solid plan, and the right financial tools.

Here are some of the most common pitfalls — and how to avoid them using AGCU’s services to build a stronger financial future

Avoiding Common Money Mistakes

1. Ignoring Your Financial Situation

The Problem:
It’s easy to coast through daily life without knowing how much money is in your account, how much debt you owe, or even what your credit score is. But ignoring your finances can lead to overdrafts, missed payments, and a lack of savings when you need it most.

The Fix:
Take time to regularly check your balances, track spending, and monitor your progress toward financial goals. Budgeting apps, online banking tools, and simple spreadsheets can help you stay organized.

AGCU Solution:
Use Online & Mobile Banking to track your accounts anytime, anywhere. And make your money work harder with a FREE Loyalty Plus High Yield Checking Account — you’ll earn competitive interest just by managing your money well.

2. Not Having Clear Financial Goals

The Problem:
Without goals, it’s easy to spend impulsively and wonder where your money went. A lack of direction can lead to missed opportunities and little progress toward long-term dreams.

The Fix:
Set short-term and long-term goals — like building an emergency fund, saving for a home, or preparing for retirement. Goals help you focus your spending and stay motivated.

AGCU Solution:
Open a Savings Account to get started, or Money Market Account for higher returns and easy access to your funds. Planning for retirement? Consider an IRA to help your savings grow tax-advantaged over time.

3. Failing to Communicate About Money

The Problem:
Many couples or families avoid talking about money to prevent conflict — but this often leads to confusion, mismatched priorities, and financial stress.

The Fix:
Set time aside for open, honest money conversations. Align on spending habits, savings goals, and shared responsibilities to build trust and teamwork.

AGCU Solution:
Use Shared Accounts to make managing household finances easier, and explore tools like online bill pay and alerts to stay in sync and avoid surprises. All of these are included for FREE with AGCU Online and Mobile Banking.

4. Not Planning for Medical Expenses

The Problem:
Medical costs can pop up unexpectedly, and without a plan in place, they can derail your budget or lead to debt.

The Fix:
Start saving ahead for future health-related needs. A dedicated account helps ensure you’re financially prepared for out-of-pocket expenses.

AGCU Solution:
Open a Health Savings Account (HSA) to save pre-tax dollars for qualified medical expenses. Funds roll over year to year, and you stay in control of how and when they’re used.

5. Letting Savings Sit Idle

The Problem:
Many people leave money in basic accounts that don’t earn much interest — which means you’re missing out on potential growth.

The Fix:
Reevaluate where you’re storing your savings. Even small improvements in your interest rate can add up over time.

AGCU Solution:
Upgrade your savings strategy with a FREE Loyalty Plus High Yield Checking Account or Money Market Account. These options offer higher returns while keeping your money accessible. Or, if you won’t need immediate access to funds, consider a CD for more competitive rates.

6. Not Building an Emergency Fund

The Problem:
Life is unpredictable — and without an emergency fund, even a small surprise expense can throw off your finances or push you into debt.

The Fix:
Aim to save at least a few months’ worth of expenses. Set up automatic transfers to make saving consistent and painless.

AGCU Solution:
Start with an AGCU Savings Account, and set up recurring transfers from your checking account to grow your cushion over time.

7. Relying Too Much on Credit

The Problem:
It’s easy to fall into the habit of swiping now and worrying later. High-interest credit card debt can build quickly and make it harder to save.

The Fix:
Use credit responsibly, and focus on paying down high-interest balances first. Be mindful of your credit utilization to protect your credit score.

AGCU Solution:
AGCU offers low-rate credit cards and personal loans to help you manage or consolidate debt. Use these tools to regain control and reduce interest costs.

Start Smart, Stay Strong

Avoiding these common money mistakes can help you build financial stability and confidence. Whether you’re just starting your savings journey or optimizing your current strategy, AGCU offers tools to help you succeed every step of the way — from checking and savings accounts, to IRAs, Health Savings Accounts, credit cards, and more.

💡 Ready to take control of your financial future? Learn more about Banking with a Purpose and open an account today.

Banking With A Purpose

Much more than a catchphrase, our tagline is our passion, our reason why we do what we do. This is the impact of your membership with AGCU. Learn More About Banking with a Purpose

Like us on Facebook!

Is My Tax Refund Too Large?

Tax season is here, and if you’re expecting a big refund, you might be feeling like you hit the jackpot! But before you start planning how to spend that extra cash, it’s important to ask: Is my tax refund too big? Let’s break down what it means when you receive a large refund, why it may not be in your best interest, and what steps you can take to better manage your money throughout the year.

12 Steps to Financial Wellness-Step 3: Pay Down Debt

12 Steps to Financial Wellness

Step 3: Pay Down Debt

Create a practical payoff plan, reduce the cost of borrowing and take another important step toward greater financial freedom.

Your Financial Wellness Journey Step 3 of 12

You have tracked your spending and created a budget for your monthly expenses. Now it is time to use what you have learned to address one of the biggest obstacles to financial wellness: debt.

Paying down debt may take time, but you do not have to tackle everything at once. A clear plan, consistent payments and steady progress can help you regain control of your finances.

1

Organize Your Debt

Start by creating a complete list of the money you owe. Include credit cards, personal loans, vehicle loans, medical debt, student loans and any other outstanding balances.

For each debt, record:

  • The name of the lender or creditor
  • Your current balance
  • The interest rate
  • Your required minimum payment
  • The monthly due date

Seeing all your debts in one place can feel intimidating, but it gives you the information you need to create an effective payoff strategy.

Creditor Balance Interest Rate Minimum Payment Due Date


2

Choose Your Payoff Strategy

Two common debt-payoff strategies are the debt snowball and the debt avalanche. Both can work. The best choice is the one that keeps you motivated and fits your financial circumstances.

Motivation Focused

Debt Snowball

Make the minimum payment on every debt, then direct all available extra money toward your smallest balance.

When that debt is paid off, apply its former payment to the next-smallest balance.

Potential advantage: Paying off smaller debts quickly can provide encouragement and build momentum.

Interest Focused

Debt Avalanche

Make the minimum payment on every debt, then direct all available extra money toward the balance with the highest interest rate.

After that debt is paid, move to the debt with the next-highest rate.

Potential advantage: This approach may reduce the total amount of interest you pay.

3

Increase Your Payments

Minimum payments can keep an account current, but they may not reduce the balance very quickly—especially when the interest rate is high. Look for realistic ways to add more to your targeted debt each month.

  • Reduce spending in one or two flexible budget categories.
  • Cancel subscriptions or services you no longer use.
  • Apply bonuses, gifts or other unexpected income to your debt.
  • Use part of a tax refund for an additional principal payment.
  • Sell unused belongings and apply the proceeds to your balance.
  • Consider temporary freelance, overtime or part-time work.

You do not need a large amount of extra money to make progress. Consistently adding even a modest amount to your payment can reduce your balance and shorten your payoff timeline.

4

Consider Debt Consolidation

Debt consolidation combines multiple balances into a single loan. If the new loan has a lower interest rate and affordable payment, consolidation may make your debt easier to manage and reduce the amount of interest you pay.

Before consolidating, compare:

  • The new interest rate and annual percentage rate
  • Any origination fees or other loan costs
  • The length of the repayment term
  • The total amount you will repay over the life of the loan
  • Whether the monthly payment fits comfortably within your budget

A lower monthly payment is not always a better deal if it extends the debt for several additional years. Review the full cost—not only the payment amount.

5

Talk With Your Creditors

Contacting a creditor may feel uncomfortable, but asking about your options can be worthwhile—especially before you miss a payment.

Depending on the lender and your circumstances, options may include:

  • A lower interest rate
  • A temporary hardship plan
  • A modified payment schedule
  • A changed payment due date
  • Waived or reduced fees

Explain your situation honestly, ask what assistance may be available and make sure you understand the terms before agreeing to a new payment arrangement.

Your Debt-Payoff Action Plan

  • List every outstanding debt and its details.
  • Select the snowball or avalanche method.
  • Decide how much extra you can pay each month.
  • Set up automatic minimum payments when appropriate.
  • Track your declining balances and celebrate milestones.
  • Review your plan whenever your income or expenses change.

Could Consolidating Your Debt Help?

An AGCU personal loan may help you combine eligible balances into one predictable monthly payment. Compare the rate, term and total cost carefully to determine whether consolidation is appropriate for your financial situation.

Explore Personal Loans Contact AGCU
Important: This article is provided for general educational purposes and is not financial, legal, credit or tax advice. Loan approval, rates and terms are subject to creditworthiness, eligibility and AGCU underwriting requirements. Consolidating debt may not reduce your total repayment cost in every situation. Membership eligibility applies. Federally insured by NCUA.

12 Steps to Financial Wellness-Step 2: Creating a Budget

12 Steps to Financial Wellness

Step 2: Create a Budget

Turn what you learned by tracking your spending into a practical plan for paying expenses, reaching goals and using your money with purpose.

Your Financial Wellness Journey Step 2 of 12

A budget is not a punishment or a list of everything you are not allowed to buy. It is a plan for your money. A thoughtful budget helps you cover your responsibilities, prepare for future expenses and make room for the things that matter most to you.

If you completed Step 1 and tracked your spending, you already have much of the information you need. Now you can use those numbers to build a realistic monthly plan.

1

Calculate Your Monthly Income

Begin with the money you can reasonably expect to receive each month. Use your take-home pay—the amount available after taxes, insurance and other payroll deductions.

  • Paychecks from regular employment
  • Self-employment or freelance income
  • Social Security, pension or retirement income
  • Child support or other dependable payments
  • Any additional income you receive consistently

If your income changes from month to month, consider using a conservative average based on several months of earnings. Building your budget around a lower, dependable amount can help you avoid committing money that may not arrive.

2

List Your Monthly Expenses

Review your statements, bills and spending records. Include both fixed expenses that stay about the same and variable expenses that may change from month to month.

Expense Type Examples Budgeted Amount
Housing Mortgage or rent, utilities, insurance and maintenance $
Transportation Vehicle payment, fuel, insurance, repairs and transit $
Food Groceries, dining out, coffee and convenience purchases $
Debt Payments Credit cards, loans, medical debt and student loans $
Savings and Goals Emergency savings, retirement, vacations and major purchases $
Personal and Family Clothing, childcare, entertainment, hobbies and subscriptions $
Giving Tithes, charitable donations and community support $
3

Separate Needs From Wants

Needs are expenses required for basic living, health, safety and financial obligations. Wants are purchases that may improve your comfort or enjoyment but can usually be reduced, delayed or replaced when necessary.

The distinction is not always simple. Internet access may be a necessity for work or school, while a premium entertainment package is likely a want. Groceries are a need, while frequent restaurant meals are generally more flexible. The goal is not to criticize your choices—it is to understand where you have room to adjust.

  • Needs: Housing, basic utilities, food, medicine, transportation and required debt payments
  • Wants: Entertainment, optional subscriptions, upgrades, hobbies and convenience spending
  • Goals: Savings, investing, giving and planned future purchases
4

Assign Every Dollar a Purpose

Compare your expected income with your planned expenses. Your budget should account for the full amount of money available, including amounts designated for savings, giving and financial goals.

Monthly Income − Planned Expenses − Savings and Goals = $0 Unassigned

A zero-based plan does not mean spending every dollar. It means every dollar has a job. Money directed toward an emergency fund, retirement account or future expense is still part of the plan.

If your expenses exceed your income, begin by reviewing flexible categories. Look for changes that are realistic and sustainable rather than cutting every enjoyable expense at once.

5

Choose a Budgeting System

There is no single budgeting method that works for everyone. Consider your personality, financial responsibilities and preferred level of detail.

Traditional Category Budget

Set a monthly limit for each spending category, then review your transactions throughout the month. This method works well for people who prefer detailed planning and regular tracking.

Envelope System

Assign cash—or digital spending limits—to flexible categories such as dining, entertainment and personal spending. When the category is empty, spending stops until the next budget period.

50/30/20 Framework

As a general guideline, direct about 50% of take-home pay to needs, 30% to wants and 20% to savings and debt repayment. Your actual percentages may need to differ based on housing costs, income and family needs.

6

Review and Adjust Your Plan

Your first budget is a starting point, not a permanent contract. Review your spending during the month and compare it with your plan. Adjust categories when costs change or when your original estimate was unrealistic.

  • Review transactions at least once each week
  • Adjust for seasonal bills and annual expenses
  • Update your plan after changes in income or household needs
  • Include a small cushion for expenses that are difficult to predict
  • Revisit your goals and priorities regularly

A budget should become more accurate over time. Learning from each month is part of the process.

This Month’s Budget Challenge

Create a complete budget for the upcoming month before it begins. Schedule a short weekly check-in to compare your plan with your actual spending. At the end of the month, identify one category that worked well and one that needs adjustment.

Keep Your Budget Connected to Your Accounts

AGCU Online Banking can help you review transactions, monitor account activity and stay aware of your spending throughout the month. Regular check-ins make it easier to keep your budget current and make adjustments before small problems become larger ones.

Log In to Online Banking Explore Digital Banking
Important: This article is provided for general educational purposes and is not financial, legal, credit or tax advice. Digital Banking features and availability may change. Membership eligibility applies. Federally insured by NCUA.