
13 Steps to Manage Debt: Taking Back Control of Your Finances
A practical guide to reducing debt, lowering stress, and building a healthier financial future.
Managing debt doesn’t have to feel overwhelming. With the right plan, you can take control of your finances, reduce high-interest balances, and create a path toward financial freedom.
Whether you’re dealing with credit cards, personal loans, student loans, or a combination of debts, these steps can help you move forward with confidence.

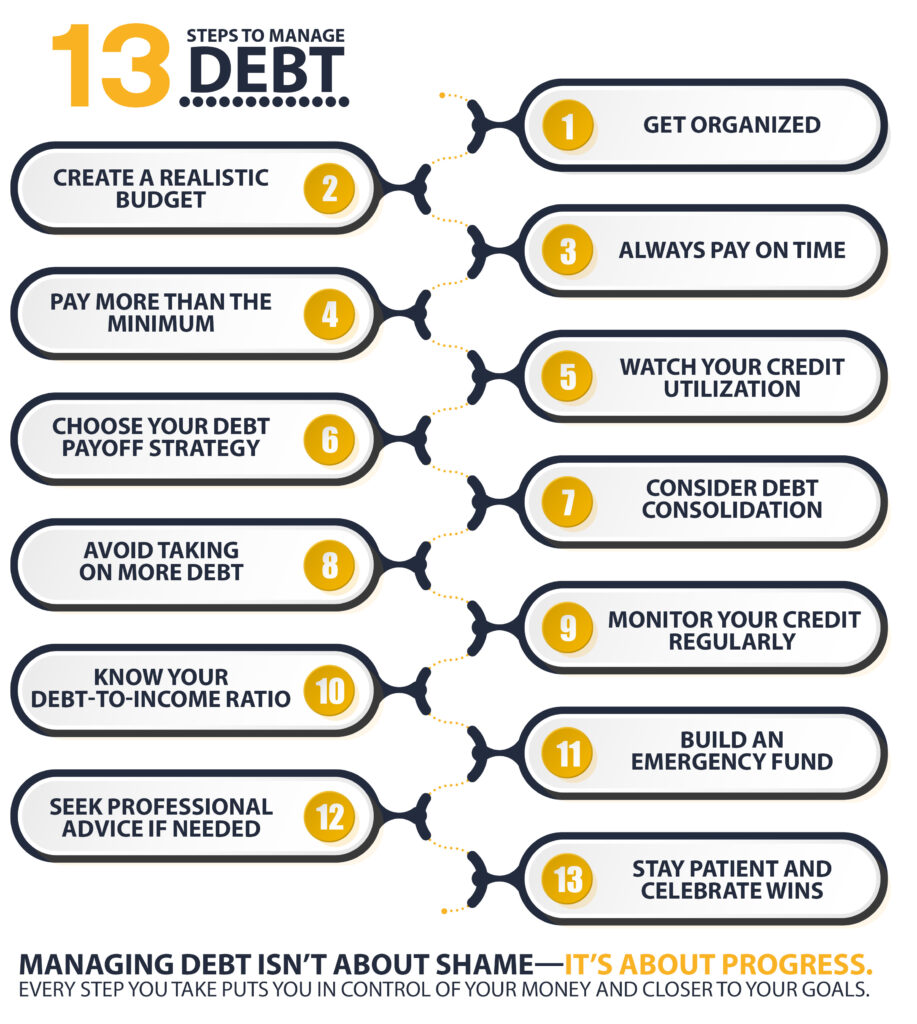
Step 1: Know Exactly What You Owe
Start by creating a complete list of your debts, including balances, interest rates, minimum payments, and due dates.
You can’t build a payoff plan until you know where you stand.
Step 2: Create a Realistic Budget
A budget gives every dollar a purpose. Track your income, fixed expenses, and discretionary spending so you can identify money that can be redirected toward debt reduction.
Focus on progress, not perfection.
Step 3: Stop Adding New Debt
Before accelerating your payoff plan, work on preventing balances from growing. Consider limiting credit card use and relying more on cash, debit cards, or a spending plan.
Step 4: Choose a Payoff Strategy
Debt Snowball
Focus on paying off the smallest balance first while making minimum payments on everything else. This creates quick wins and momentum.
Debt Avalanche
Focus on the highest interest rate debt first. This approach often saves the most money over time.
Step 5: Pay More Than the Minimum
Minimum payments keep accounts current, but they can significantly extend repayment timelines.
Even an additional $25–$50 per month can reduce interest costs and help you become debt-free sooner.
Step 6: Consider Debt Consolidation
If you’re juggling multiple payments, consolidating debt into a single loan may simplify repayment and potentially lower your interest costs.
Consolidation works best when paired with healthy spending habits and a realistic repayment plan.
Step 7: Negotiate When Possible
Some creditors may be willing to work with you if you’re experiencing financial hardship. Ask about:
- Temporary hardship programs
- Lower interest rates
- Modified payment plans
- Fee reductions
Step 8: Monitor Your Credit
Regularly reviewing your credit report helps you track progress, identify errors, and spot signs of fraud.
Paying down debt can improve your credit profile over time.
Step 9: Reduce Unnecessary Spending
Small adjustments can create extra cash flow for debt reduction.
- Review subscriptions
- Limit impulse purchases
- Shop with a list
- Delay nonessential purchases
Step 10: Increase Your Income
Temporary side income, overtime opportunities, freelance work, or selling unused items can help accelerate debt payoff and build financial momentum.
Step 11: Build an Emergency Fund
One reason debt often grows is the lack of a financial cushion when unexpected expenses occur.
Start with a goal of $500–$1,000, then gradually work toward three to six months of living expenses. This helps reduce the need to rely on credit when emergencies arise.
Step 12: Seek Professional Guidance
If debt feels overwhelming, a reputable credit counselor can help you develop a repayment strategy and communicate with creditors.
Look for organizations that are transparent, accredited, and focused on education rather than sales.
Step 13: Stay Patient and Celebrate Progress
Debt reduction is rarely an overnight process. Every balance paid down, every extra payment made, and every financial habit improved is a step forward.
Celebrate milestones along the way and keep your focus on long-term progress.
How AGCU Can Help
AGCU offers tools that may help you regain control of your finances, including:
- Debt consolidation loans
- Personal loans
- Low-rate credit cards
- Savings accounts for emergency funds
- Financial education resources
The right combination of tools and habits can make a meaningful difference in your financial journey.
Frequently Asked Questions
What’s the difference between the debt snowball and debt avalanche methods?
The snowball method focuses on the smallest balances first for quick wins, while the avalanche method targets the highest interest rates first to save more money over time. :contentReference[oaicite:8]{index=8}
Should I build an emergency fund or pay off debt first?
Many financial professionals recommend doing both—building a small emergency fund while continuing to make debt payments. :contentReference[oaicite:9]{index=9}
Is debt consolidation a good idea?
It can be helpful if it simplifies payments or lowers interest costs, but it should be paired with a plan to avoid taking on additional debt. :contentReference[oaicite:10]{index=10}
How long does it take to become debt-free?
The timeline varies based on your balances, interest rates, and monthly payments. Consistency is more important than speed. :contentReference[oaicite:11]{index=11}
Final Thought
Managing debt isn’t about shame—it’s about progress.
Every step you take puts you in control of your money and moves you closer to financial freedom. Whether you’re just getting started or making steady progress, remember that small, consistent actions add up over time. :contentReference[oaicite:12]{index=12}